

Blogs
How Military Protective Eyewear Market’s 6.78% CAGR Reshapes Procurement Strategy
By PW Consulting, 2026-09-18
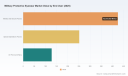
The Global Military Protective Eyewear Market: Strategic Trends and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
The worldwide military protective eyewear market has demonstrated sustained momentum, evolving from a niche procurement category into a strategically significant segment of defense logistics and soldier modernization. Between 2020 and 2025, market revenue expanded steadily, reflecting consistent procurement cycles, incremental capability upgrades, and the widespread institutionalization of eye protection as a baseline combat requirement. This upward trajectory is projected to persist through the 2026–2032 forecast horizon, supported by a compound annual growth rate that underscores the segment's resilience and strategic relevance. The market's scale now positions protective eyewear as an integral component of force readiness rather than an ancillary accessory, with procurement volumes increasingly tied to fleet-wide modernization initiatives and coalition interoperability standards.
Despite this favorable backdrop, industry participants navigate a complex operating environment defined by several structural tensions. First, the dual mandate of meeting rigorous ballistic performance thresholds while maintaining ergonomic comfort, optical clarity, and environmental adaptability creates a persistent engineering balancing act. Specifications such as MIL-PRF-32432 and MIL-PRF-31013 establish demanding impact-resistance criteria, requiring products to withstand high-velocity fragments without compromising field usability. At the same time, the Authorized Protective Eyewear List framework introduces a procurement dynamic where approval status, logistical compatibility, and mission-specific suitability directly influence adoption rates. Manufacturers must therefore align technical performance with procurement workflows and user acceptance patterns, a challenge that intensifies as operational environments grow more varied.
Worldwide Military Protective Gear Market
Second, supply chain and cost structures introduce volatility that reverberates across the value chain. The market's concentration profile, with a notable share held by a relatively small group of established players, highlights both the barriers to entry and the operational scale required to compete effectively. Splitting production across specialized component sourcing, optical coating, frame manufacturing, and stringent quality assurance means that raw material fluctuations, logistics disruptions, or certification delays can quickly translate into margin compression. For buyers, this translates into procurement cycles that must account for lead-time management and qualification timelines; for manufacturers, it underscores the importance of resilient sourcing strategies and modular design architectures that can accommodate supply variability without sacrificing compliance.
Third, the market sits at a transition point driven by evolving threat profiles and changing procurement philosophies. Modern combat scenarios increasingly involve asymmetric threats, urban engagements, and multi-domain operations where fragmentation, laser-based systems, and environmental hazards coexist. This shifts the priority from baseline protection toward integrated capability sets that can adapt across missions. At the same time, budget cycles and multinational procurement programs favor standardization, interoperability, and lifecycle cost considerations. Companies that can demonstrate not only compliance but also operational value—reduced injury incidence, improved situational awareness, clearer optics under varied lighting, and streamlined maintenance—are better positioned to secure sustained demand in an environment where procurement decisions increasingly weigh total value rather than unit price alone.
Key Drivers Reshaping the Market
Several interrelated forces are shaping the direction of the military protective eyewear market, each reinforcing the others and creating distinct implications for product strategy, procurement planning, and competitive positioning.
Technological innovation continues to redefine what protective eyewear can deliver in the field. The dominant product category remains ballistic spectacles, reflecting the enduring requirement for high-velocity impact and fragment protection in operational settings. Yet the performance envelope is expanding well beyond baseline impact resistance. Photochromic and polarized lens technologies, for example, address real-world visibility challenges by adapting to changing light conditions and reducing glare without sacrificing ballistic integrity. Anti-fog coatings, moisture-management frame designs, and prescription-compatible configurations further bridge the gap between protection and sustained operational usability. These enhancements are not cosmetic; they respond directly to the practical demands of extended deployments, fast-paced engagements, and environments where visual performance influences both safety and mission effectiveness. As a result, differentiation increasingly emerges from the integration of multiple functional capabilities rather than from a single standout feature.
Worldwide Military Wearable Market
Policy and regulatory frameworks act as both gatekeepers and accelerators. In the U.S. context, the requirement to meet MIL-PRF standards ensures a high floor for performance, while the Authorized Protective Eyewear List provides a procurement mechanism that shapes which products gain field traction. The existence of a formal approval pathway creates predictability for suppliers that invest in compliance, but it also raises the stakes for entry, since qualification is a prerequisite for large-scale adoption in many programs. Outside the U.S., comparable standards and multinational procurement expectations are increasingly influencing product development priorities. ANSI/ISEA Z87.1 remains a widely recognized baseline, but military applications often exceed that threshold through additional ballistic, optical, and environmental performance requirements. This layered standards environment rewards manufacturers that can navigate both commercial safety benchmarks and defense-specific certification regimes, while also aligning product roadmaps with anticipated specification updates.
On the demand side, shifting procurement behavior and user expectations are altering the value proposition. Rising global defense expenditures and soldier modernization programs continue to drive demand for advanced military protective eyewear across major NATO and allied forces. This is not merely a volume story; it reflects a broader modernization philosophy in which individual equipment is evaluated as part of an integrated soldier system. Procurement teams increasingly look for solutions that support interoperability, reduce logistical complexity, and perform reliably across training and combat conditions. End-user preferences also play a growing role, as operators favor gear that is comfortable, lightweight, and adaptable without compromising protection. When products are perceived to enhance mission readiness—through better optics, fewer field adjustments, or seamless compatibility with helmets and other tactical equipment—adoption momentum strengthens accordingly.
Supply chain and cost dynamics form the fourth major driver. The market's structure favors organizations that can manage complexity at scale, balancing component sourcing, manufacturing precision, and qualification rigor. Recent activity illustrates how companies are responding to these pressures through contract wins, certification milestones, and new product introductions. Several manufacturers have secured framework agreements and specialized program awards that underscore the importance of reliable supply and proven compliance. At the same time, the launch of newer eyewear systems at major industry events signals continued investment in capability upgrades and platform compatibility. These developments point to a competitive environment in which operational reliability, certification readiness, and program execution are becoming as important as product features alone. Cost management is therefore not just a procurement concern but a strategic capability: companies that can maintain performance and compliance while controlling total cost of ownership are better equipped to win multi-year programs and defend margins in a market that rewards consistency.
Competitive Landscape and Leading Strategies
The competitive environment in military protective eyewear is defined by a small group of entrenched manufacturers that combine technical capability, program experience, and established relationships with procurement authorities. Market concentration reflects the realities of certification, scale, and long-cycle defense procurement, but it also leaves room for differentiation through product architecture, mission-specific configuration, and execution reliability. Several companies have built leading positions by aligning their offerings with the dual demands of ballistic performance and field usability, while also pursuing strategic moves that extend their reach across programs and operating environments.
Revision Military has maintained a strong profile as a specialist in ballistic and performance eyewear for military and tactical users. Its portfolio spans multiple systems designed to meet rigorous standards and serve diverse operator requirements, and recent developments highlight a dual focus on contract execution and product qualification. The company's activities in 2025, including supplying special forces with established eyewear systems and securing national stock number recognition for a goggle kit for U.S. military use, illustrate how qualification milestones and targeted program wins can reinforce market presence. An earlier framework contract with the NATO Support and Procurement Agency points to a longer-term strategy centered on multinational relevance and supply chains that can support coalition requirements. This combination of product breadth, certification progress, and institutional engagement positions the company to compete where interoperability and proven compliance matter.
Gentex Corporation occupies a distinct position through its emphasis on advanced eyewear and optics for both ground forces and aircrew. Its product portfolio includes ballistic eyewear systems and laser eye protection solutions, and recent program activity demonstrates the company's ability to engage with specialized requirements. The launch of an updated ballistic eyewear system at a major industry showcase signaled continued investment in platform-compatible design and field-oriented performance. Equally notable was the award of a U.S. Air Force aircrew laser eye protection program, which reflects demand for mission-specific optical solutions that address distinct threat environments. This blend of ground and aircrew focus suggests a strategy oriented around capability breadth and program specialization, where value is created not only through protection but also through optical performance tailored to specific operational roles.
Other established players contribute to a competitive field shaped by different strengths. ESS Eye Pro emphasizes high-performance impact protection for military, law enforcement, and tactical use, with a product set built around ballistic goggles, sunglasses, and eyeshields that meet recognized safety standards. Oakley Standard Issue leverages brand recognition and optical engineering to supply ballistic sunglasses and tactical eyewear designed for helmet compatibility and clarity, with products aligned to military procurement specifications. Wiley X focuses on tactical and ballistic-rated eyewear featuring high-velocity impact protection and interchangeable lens systems, an approach that supports adaptability across environments. Bolle Safety and uvex bring European manufacturing heritage and defense-adjacent safety expertise, with product lines and industry affiliations that reinforce their relevance in multinational and special-forces contexts. American Optical draws on a long supply history with the U.S. military and a specification-driven approach to military eyewear, reinforcing a positioning rooted in proven pedigree and compliance orientation.
What distinguishes these leaders is not only product performance but strategic positioning. Leading manufacturers tend to pursue a combination of certification readiness, program execution, and mission-specific configuration. They invest in meeting or exceeding military specifications, while also developing product architectures that simplify field use, maintenance, and compatibility with other equipment. The result is a market in which success increasingly depends on the ability to deliver consistent compliance, reliable supply, and practical operability rather than on a single breakthrough feature. At the same time, the landscape appears to be evolving along multiple axes. Consolidation pressure exists where scale, qualification expertise, and program relationships create advantages for larger or well-connected players. At the same time, differentiation remains possible through specialized solutions, such as laser protection for aircrew, advanced lens technologies for varied lighting conditions, or configurations optimized for special operations. New entrants face meaningful hurdles, but niche positioning around particular mission needs, coalition procurement pathways, or complementary technologies can create viable avenues for growth.
Forward Outlook: Trends and Commercial Implications
Looking ahead across the 2026–2032 period, several trends are likely to shape the market's direction and create distinct commercial implications. The first is the continued shift from baseline protection to integrated capability. As operational environments become more complex, demand will increasingly favor eyewear that combines ballistic resilience with optical versatility, environmental durability, and compatibility with broader soldier systems. Products that can reduce the number of separate accessories operators must carry, or that support rapid adaptation across training and combat conditions, are well placed to capture attention in modernization programs. Commercial opportunity here lies in modular designs, advanced lens technologies, and configurations that simplify logistics while preserving performance across mission profiles.
A second trend is the growing importance of specialized protection segments within the broader market. Laser eye protection for aircrew and other specialized roles illustrates how threat-specific requirements can create focused demand streams that reward targeted development and program specialization. These segments may not dominate total volume, but they often carry higher value intensity and stronger differentiation potential because they address distinct operational needs. Manufacturers that cultivate capability depth in these areas can build defensible positions, particularly where certification pathways and program relationships reinforce repeat engagement. The commercial implication is that companies should evaluate not only overall market growth but also the relative attractiveness of sub-segments where technical complexity and mission specificity support stronger positioning.
A third trend concerns procurement architecture and multinational alignment. Rising defense expenditures and soldier modernization programs across major allied forces are likely to sustain demand, but procurement decisions will increasingly emphasize standardization, interoperability, and lifecycle performance. Framework agreements, stock number recognition, and approval-list dynamics will continue to shape how products move from qualification to field adoption. For suppliers, this means that commercial success may depend as much on navigating procurement processes and demonstrating total value as on product innovation alone. For buyers, the implication is that supplier selection should account for qualification status, supply reliability, and support for multi-year logistics needs, not just unit specifications.
These trends carry inherent uncertainty. Budget cycles can shift procurement timing; standards may evolve in ways that change qualification requirements; and supply chain disruptions can affect delivery confidence. In addition, the balance between performance enhancement and cost control will remain a persistent pressure point. Companies and buyers alike should therefore treat the market's direction as promising but contingent, with success depending on adaptability, program execution, and the ability to translate technical advantage into procurement-relevant value.
PW Consulting
Strategic Actions for Decision Makers
Different stakeholder groups can extract actionable value from the current market dynamics by aligning their strategies with the forces most relevant to their positions.
-
For manufacturers, the priority is to strengthen the link between compliance, operability, and program execution. This means treating certification readiness as a strategic asset, investing in product architectures that support modularity and field adaptability, and building supply-chain resilience that protects delivery confidence. Differentiation is increasingly gained through the ability to meet military specifications reliably while also reducing logistical friction and enhancing mission usability. Companies should also evaluate where specialized capabilities—such as laser protection, advanced lens systems, or coalition-friendly configurations—can create stronger positioning than broad commodity competition.
-
For investors, the relevant question is not simply whether the market is expanding, but where value is being created and sustained. Market growth is supported by modernization programs and rising defense expenditures, but profitability and competitive durability depend on execution capability, certification access, and differentiation in higher-intensity segments. Attention should focus on organizations that demonstrate consistent program wins, credible qualification pathways, and product strategies that align with evolving procurement priorities. At the same time, risk awareness is essential, particularly around standards evolution, supply variability, and the concentration dynamics that shape entry barriers and competitive intensity.
-
For procurement and program leaders, the actionable insight is to evaluate protective eyewear not only as a compliance item but as a readiness enabler with total-cost implications. Selection criteria should account for approval status, supply reliability, optical performance in realistic conditions, compatibility with helmets and other equipment, and support for lifecycle management. Where programs span multiple forces or coalition environments, interoperability and standardization should carry additional weight. A disciplined evaluation framework that balances protection, usability, and logistical reliability can improve both field outcomes and procurement resilience.
The commercial stakes in this market are rising alongside its strategic importance. Decision makers looking to navigate segmentation detail, procurement pathways, competitive positioning, and forward scenario implications will find value in more granular research that ties market structure to actionable planning parameters. Further analysis of segment-specific dynamics, company-level capability assessments, and procurement-aligned forecasts can help translate these high-level trends into decisions that hold up under program scrutiny.
For detailed analysis of this topic, please visit the official page: Worldwide Military Protective Eyewear Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Computer on Wheels Market: Why 14.5% CAGR Through 2032 Changes Everything
By PW Consulting, 2026-09-18
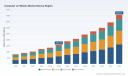
Strategic Trends and Commercial Opportunities in the Worldwide Computer on Wheels Market
Market Landscape and Core Challenges
The global computer on wheels (COW) market has demonstrated robust expansion over the past half-decade, transitioning from a niche healthcare mobility segment to a mainstream component of clinical infrastructure. Market valuation placed the sector at approximately USD 1,577.16 million in 2025, reflecting consistent year-over-year growth from a base of USD 801.4 million in 2020. Forward-looking projections indicate a compound annual growth rate of 14.5 percent through 2032, with revenue anticipated to surpass USD 4 billion by the end of the forecast horizon. This trajectory underscores a structural shift rather than cyclical fluctuation, as healthcare delivery models increasingly prioritize bedside documentation, mobile diagnostics, and real-time electronic medical record access. Regional and product-type dynamics reveal a mature but still evolving demand pattern, with powered systems commanding the largest share of revenue while non-powered alternatives maintain relevance in cost-sensitive or space-constrained environments.
Despite the favorable growth trajectory, the industry faces several structural headwinds that will shape competitive positioning over the next decade. First, regulatory scrutiny around medical device compliance continues to tighten across multiple jurisdictions. Electrical safety, electromagnetic compatibility, and infection control standards now function as baseline requirements rather than differentiators, forcing manufacturers to embed compliance into design cycles rather than retrofitting existing platforms. Second, the integration of advanced battery and power management systems has introduced both an operational imperative and a supply chain vulnerability. Lithium iron phosphate packs with hot-swap capabilities have become the de facto infrastructure for sustained clinical operation, yet sourcing, lifecycle management, and replacement logistics remain fragmented across the vendor ecosystem. Third, labor cost pressures and nursing workflow inefficiencies are driving demand for mobility solutions, but procurement cycles in healthcare systems remain lengthy and highly sensitive to total cost of ownership calculations. Organizations must navigate the tension between immediate workflow gains and long-term capital justification, which can delay adoption in budget-constrained settings.
The market is also approaching a consolidation inflection point. Revenue concentration among the top three and top five participants indicates a moderately fragmented landscape with clear leadership clusters, but the presence of specialized regional suppliers and custom-configuration providers suggests that differentiation will increasingly hinge on integration depth, service networks, and lifecycle support rather than pure hardware specifications. Companies that treat COW deployments as static equipment purchases risk losing ground to competitors who position these systems as configurable, service-enabled platforms aligned with clinical workflow evolution.
Medical Computer Cart Market
Key Drivers Shaping Market Evolution
Several interdependent forces are accelerating demand and reshaping product requirements across the COW sector. At the technology frontier, the convergence of low-profile computing architectures, ruggedized enclosures, and modular battery ecosystems has redefined what mobile workstations can deliver at the point of care. Patented fast-swap battery technologies and lithium iron phosphate systems with hot-swap capabilities now enable continuous operation without downtime, which is critical for hospitals running extended clinical shifts. Manufacturers have responded by designing carts that accommodate third-party computing modules or integrate all-in-one medical-grade displays, allowing facilities to standardize on a mobility platform while retaining flexibility in processor selection, operating system configuration, and peripheral attachment. This modularity reduces replacement friction and extends asset longevity, aligning hardware refresh cycles with clinical IT roadmaps rather than forcing simultaneous upgrades across every deployment.
Policy and regulatory environments are acting as both a constraint and a catalyst. Healthcare computer on wheels systems must comply with medical device standards for electrical safety, electromagnetic compatibility, and infection control in hospital environments. Rather than treating these requirements as purely defensive, leading manufacturers are using compliance as a trust signal and a design anchor. Standardized certification pathways reduce procurement friction for health systems, while infection-control features such as seamless surfaces, antimicrobial coatings, and easily disinfected contact points are increasingly specified in tender documents. In parallel, broader digital health policies that encourage electronic medical record adoption and bedside data capture indirectly expand the addressable base for mobile workstations, since facilities investing in digital workflows require reliable, mobile access points that move with clinicians rather than anchor them to fixed terminals.
On the demand side, the most pronounced shift is the operational response to labor cost pressures and workflow inefficiency. Mobile computer on wheels reduce time spent by nurses walking to stationary terminals, supporting workflow efficiency in point-of-care documentation. This logistical benefit translates into measurable time savings during documentation, medication administration, and bedside rounding, which in turn influences purchasing decisions among nursing leadership and clinical operations teams. Beyond time savings, the expectation for real-time data access has raised the stakes for device reliability. Clinicians increasingly view mobile workstations as extensions of the clinical team rather than peripheral equipment, which elevates expectations for uptime, ergonomic design, and seamless docking or charging behavior. Facilities that have deployed sit-to-stand configurations or customizable workstation heights are reporting improved clinician acceptance, suggesting that ergonomics and usability have become as important as raw computing capability.
Supply chain and cost structure changes are also reshaping competitive dynamics. The shift toward battery-centric infrastructure has introduced a recurring component management dimension to what was historically a one-time capital purchase. Hot-swap battery packs and modular power systems create opportunities for repower services, warranty extensions, and lifecycle support contracts, converting some hardware revenue into longer-duration service relationships. At the same time, ISO-certified manufacturers with established export experience are expanding their footprint into global healthcare markets, increasing price and specification competition in regions where procurement teams balance clinical-grade requirements against budget constraints. This dynamic is encouraging both incumbents and new entrants to clarify their value propositions: whether they compete on integration depth, regional service coverage, cost efficiency, or specialized workflow configurations.
Competitive Landscape and Strategic Positioning
The competitive field is anchored by a group of U.S.-based manufacturers that have built recognizable positions around customization, battery innovation, and workflow alignment. Scott-Clark Medical has carved a niche around customizable healthcare computer on wheels and mobile computer carts, with powered systems featuring patented FMCPT battery technology optimized for point-of-care use in hospitals. This battery-led differentiation gives the company a tangible engineering narrative in procurement discussions where uptime and battery reliability are primary concerns. Altus Inc. competes across both powered and non-powered medical carts, offering battery-powered computer on wheels workstations designed for hospital EMR and patient care workflows. Its broader product span allows flexibility across budget tiers and deployment contexts, which is useful for health systems standardizing across multiple units or campuses. DTG Power emphasizes battery-powered workstation on wheels solutions and LFP battery systems, and notably positions repower services for existing carts from various manufacturers. This service-oriented angle extends the company's relevance beyond new equipment sales and into lifecycle support, an increasingly important consideration for facilities managing mixed-fleet environments.
Ergotron and Capsa Healthcare illustrate complementary strategic angles within the same ecosystem. Ergotron manufactures mobile computer carts and workstations on wheels for healthcare environments, frequently integrated with third-party battery and computing solutions, which positions the brand as a flexible platform partner rather than a closed-system vendor. Capsa Healthcare produces medical carts including computer on wheels and medication workstations designed for hospital point-of-care documentation and mobile computing, aligning product design directly with documentation and medication workflows. Cybernet and Teguar approach the market from the computing-hardware side, supplying all-in-one medical computers and rugged medical computers respectively, with configurations suitable for integration into computer on wheels carts in healthcare settings. Their strength lies in hardware durability, certification readiness, and compatibility with mobile cart ecosystems, making them relevant to buyers who prioritize compute reliability and environmental resilience. DataCart adds a further dimension with customizable workstations on wheels featuring sit-to-stand capabilities, targeting healthcare mobility and point-of-care applications where ergonomics and clinician posture are decision factors.
International participants are expanding the scope of competition. All Modul GmbH develops various models of computer on wheels from budget to high-end configurations, with customization options for European healthcare markets, which allows it to address both price-sensitive and specification-driven buyers in its region. ZHAOFA Technology operates as an ISO-certified manufacturer of hospital-grade computer on wheels and mobile workstations for global healthcare markets, and its continued offering of custom hospital-grade COW and WOW systems reflects a sustained focus on export-oriented, specification-adaptable production. Convergint Innovative Medical supplies workstations on wheels and computer on wheels solutions tailored for nursing workflows and simulation labs in healthcare, underscoring a workflow-and-training orientation that resonates with academic medical centers and simulation-based training environments.
The recent dynamics across these players point to a market that is simultaneously consolidating around a few recognizable leaders and fragmenting around specialized use cases. ZHAOFA's ongoing catalog emphasis on custom hospital-grade COW and WOW systems, supported by a decade of manufacturing experience, signals that configurable production remains a viable entry and growth path for established OEMs serving international buyers. Indurock's updated analysis of COW terminology, hospital applications, and future trends in mobile computer workstations for healthcare and logistics indicates that the category itself is being refined and communicated more precisely, which benefits buyers but also raises the bar for vendors to articulate clear use-case fit. Convergint's continued promotion of WOW/COW benefits for nurses and ongoing supply for healthcare simulation and clinical use highlights how workflow advocacy and training environments are becoming explicit demand channels, not just end-point deployments.
Strategically, the most successful players are those that convert hardware into a platform story. Battery technology, repower services, ergonomic configuration, infection-control design, and simulation-ready deployment all function as differentiators when they are tied to measurable clinical outcomes or operational savings. The market is therefore moving away from generic cart specifications toward solution-level competition, where vendors are evaluated on how well their mobile workstations fit nursing workflows, EMR integration expectations, and lifecycle management requirements. New entrants that bring clear workflow alignment, regional service capacity, or cost-efficient ISO-certified manufacturing can still gain traction, but they must do so by targeting a defined segment rather than competing broadly on price alone.
Forward-Looking Trends and Commercial Implications
Over the next three to five years, several trends are likely to define how the COW market evolves and where commercial opportunities concentrate. First, battery and power management will become the central lifecycle differentiator rather than a secondary feature. As lithium iron phosphate packs with hot-swap capabilities become standard expectations in clinical settings, competitive advantage will shift toward battery reliability metrics, replacement logistics, and repower or refresh services. Manufacturers and service providers that can standardize battery health monitoring, hot-swap training, and predictable replacement cycles will be better positioned to retain customers and expand into service-based revenue. The commercial implication is clear: mobility hardware will increasingly be evaluated as part of a managed power ecosystem, and procurement decisions will weigh total uptime and service coverage alongside initial unit economics.
PW Consulting
Second, workflow-integrated configurations will gain prominence over generic mobile carts. The push to reduce nursing walking time and improve point-of-care documentation is driving demand for sit-to-stand features, ergonomic adjustability, medication-specific workstation layouts, and simulation-ready setups. This trend favors vendors that can demonstrate how a specific cart configuration supports a documented clinical pathway, whether for bedside rounding, medication administration, or training environments. Companies that invest in workflow research, clinician feedback loops, and configurable options are likely to secure stronger preference in tenders, particularly in health systems that have moved beyond pilot deployments and are standardizing across multiple units. The opportunity here lies in packaging configuration flexibility with clear guidance on which layouts fit which workflows, reducing the decision burden for procurement teams and clinical leaders.
Third, the market will see continued pressure toward regional specialization and certified manufacturing footprints. ISO-certified manufacturers with global export experience are expanding reach into international healthcare markets, while regional customizers are refining offerings for local compliance expectations and procurement norms. This creates a dual dynamic: global scale players compete on integration breadth and service networks, while regional and cost-efficient manufacturers compete on specification adaptability and price-to-performance ratios. For commercial strategy, this means that buyers will increasingly choose between standardized global platforms and locally tailored configurations depending on their compliance environment, service expectations, and budget posture. The risk for vendors is that undifferentiated hardware becomes commoditized quickly, while the risk for buyers is that over-customization complicates maintenance and standardization across sites.
Computer On Module (COM) Market
A persistent uncertainty across these trends is the pace of health system capital cycles. Even when workflow benefits are well documented, procurement timelines can stretch, especially in environments where total cost of ownership justification must compete with other clinical priorities. Supply chain stability for battery components and the consistency of infection-control compliance across product lines will also influence adoption speed. Organizations that can align their value proposition with both clinical workflow gains and predictable lifecycle economics are best positioned to navigate these uncertainties.
Actionable Recommendations for Decision Makers
For manufacturers and solution providers, the priority is to move beyond product specifications and build a defensible workflow-and-lifecycle narrative. Differentiate around battery reliability, repower or refresh services, ergonomic configurations, and infection-control design, and make those claims traceable to documented clinical or operational benefits. Tailor go-to-market messaging to specific use cases rather than broad category language, since procurement teams increasingly evaluate mobile workstations against defined workflows and service expectations. Companies that can combine configurable hardware with predictable service coverage will be better positioned to protect margin and extend customer relationships over the asset lifecycle.
For investors evaluating exposure to this segment, focus on the durability of competitive advantages rather than headline growth alone.Assess whether a target company has genuine differentiation in battery technology, service infrastructure, workflow-aligned design, or regional manufacturing scale. Examine the balance between one-time hardware sales and longer-duration service potential, since lifecycle support and repower capabilities can materially affect recurring revenue quality. Also pay attention to compliance readiness and certification positioning, as these factors influence procurement speed and customer retention in regulated clinical environments. Companies whose growth depends primarily on price competition without workflow or service differentiation carry higher exposure to margin compression as the category matures.
For healthcare procurement teams and clinical operations leaders, the most effective approach is to evaluate mobile workstations as configurable platforms integrated into documented workflows, not as interchangeable equipment purchases. Standardize on core requirements for electrical safety, electromagnetic compatibility, infection control, and battery uptime, then use configuration flexibility to address department-specific needs such as sit-to-stand ergonomics, medication workstation layouts, or simulation lab use. Where possible, prioritize vendors that can support mixed-fleet environments, provide clear battery lifecycle management, and offer training or workflow guidance for clinicians. This reduces operational friction and helps ensure that mobility investments translate into measurable time savings and documentation efficiency rather than unused capacity.
Given the speed at which battery standards, compliance expectations, and workflow preferences are evolving, detailed segment-level data and customized scenario planning remain valuable for precise decision making. Organizations preparing capital plans, product roadmaps, or procurement strategies can benefit from a fuller breakdown of regional demand patterns, product-type economics, end-user dynamics, and company-level benchmarking to ensure that commitments are aligned with the most current market structure.
For detailed analysis of this topic, please visit the official page: Worldwide Computer on Wheels Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Enclosed Track Conveyors Market: How 5.85% CAGR Drives 2032 Expansion Beyond Scale
By PW Consulting, 2026-09-18
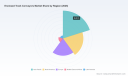
Strategic Trends and Commercial Opportunities in the Global Enclosed Track Conveyors Market
Market Overview: Current Landscape and Core Challenges
The global enclosed track conveyor industry enters the late 2020s as a mature yet steadily expanding segment within material handling and industrial automation. Valued at approximately USD 784.5 million in 2025, the market has demonstrated consistent growth from its 2020 baseline, with projections indicating a trajectory toward USD 1.17 billion by 2032. This expansion reflects a compound annual growth rate of 5.85 percent across the forecast horizon, signaling durable demand rather than cyclical volatility. The sector's resilience stems from its foundational role in overhead material transport, where enclosed track systems offer a compelling balance of load capacity, spatial efficiency, and operational safety compared to open I-beam alternatives.
However, growth trajectories are not without friction. Three structural challenges currently shape the industry's evolution. First, supply chain volatility in specialized steel profiles and precision chain components continues to influence lead times and system pricing. Enclosed track conveyors depend on engineered track geometries and hardened chain links that require controlled metallurgical processes, making upstream material availability a persistent operational variable. Second, the regulatory environment is tightening around safety and dust exposure, with updated standards introducing new compliance requirements for design, inspection, and maintenance protocols. Manufacturers and end-users must now navigate more rigorous documentation and installation verification, which raises upfront engineering costs but also creates a barrier that favors established players with mature quality systems. Third, the market faces a integration paradox: as facilities pursue smarter, data-driven operations, legacy enclosed track installations often lack native connectivity, forcing operators to weigh retrofit investments against full system replacements. This tension between operational continuity and digital upgrade paths defines much of the current procurement discourse.
Geographically, the market exhibits a clear concentration pattern, with the Asia Pacific and North America regions accounting for the largest revenue shares, followed by Europe. This distribution reflects differing industrial maturation levels, automotive and electronics manufacturing footprints, and logistics infrastructure investment cycles. Application demand remains anchored in automotive assembly and industrial finishing, while e-commerce fulfillment and food processing continue to gain incremental share as hygiene standards and flexible layout requirements intensify. The competitive structure remains moderately fragmented, with the top three suppliers capturing roughly one-third of total revenue and the top five approaching half, leaving substantial room for regional specialists and technology-differentiated entrants.
Key Demand Drivers and Structural Shifts
Technological Innovation and Modular System Design
The most visible driver of market expansion lies in the ongoing refinement of modular, enclosed track architectures that prioritize installation flexibility and maintenance efficiency. Traditional overhead conveyor deployments often required extensive structural modification and long commissioning windows. Newer system designs emphasize standardized trolley interfaces, quick-swap chain segments, and pre-engineered bend radii that reduce on-site fabrication. This modularity aligns directly with the operational reality of modern manufacturing floors and distribution centers, where production lines must be reconfigured for product mix changes, seasonal volume swings, or footprint optimization. Companies that have showcased integrated demonstrations combining enclosed track conveyors with robotic handling and automated order fulfillment illustrate how mechanical material transport is increasingly treated as a component within broader automation ecosystems rather than a standalone utility. The commercial implication is clear: system value is shifting from pure load-moving capability toward integration readiness, serviceability, and layout adaptability.
Policy, Safety Standards, and Compliance Dynamics
Regulatory and standards activity is reshaping procurement criteria across the sector. Updated safety frameworks for conveyors and related equipment now extend more explicitly to enclosed track designs, introducing provisions that address dust hazards, inspection frequency, and operational verification. These requirements do not merely add bureaucratic steps; they alter the total cost of ownership calculus. Facilities operating in finishing, powder coating, food processing, and light industrial environments must account for contamination control, surface protection, and worker exposure in ways that favor enclosed configurations over exposed alternatives. At the same time, compliance pressure rewards suppliers with documented quality management, traceable component sourcing, and field service networks capable of supporting recurring inspection cycles. The trend effectively raises the floor for market participation while creating a differentiation axis for vendors that can package safety compliance, documentation, and lifecycle support into a single procurement proposition.
Demand-Side Shifts in Manufacturing and Logistics
End-user behavior is evolving under the combined influence of labor availability pressures, throughput expectations, and facility design priorities. In automotive and heavy assembly environments, enclosed track systems continue to serve as reliable work-in-process transporters that keep floor space clear and reduce manual handling risk. In finishing and coating applications, the enclosed nature of the track helps contain overspray, protect moving components, and support cleaner_process environments. Meanwhile, e-commerce and logistics operations increasingly evaluate overhead conveyance not only for bulk movement but also for sequenced order picking, sorting integration, and ergonomically optimized workstations. This broadening application base reduces dependence on any single vertical and creates cross-sector demand for systems that can be scaled in span, speed, and load rating without major redesign. The practical outcome is a more diversified demand profile, where flexibility and hygiene considerations often compete with pure cost-per-foot arguments.
Supply Chain and Cost Structure Considerations
Cost dynamics are being reshaped by the interplay of raw material sourcing, component specialization, and service expectations. Enclosed track systems rely on engineered steel tracks, precision chains, trolleys, and drive units, meaning that fluctuations in metal pricing, motor availability, and machining capacity reverberate through project quoting and delivery schedules. At the same time, customers are increasingly sensitive to installed cost, downtime during changeovers, and long-term maintenance burden. This environment favors suppliers that can offer standardized component libraries, regional inventory positioning, and predictive maintenance guidance. It also encourages end-users to evaluate lifecycle economics more rigorously, weighing initial capital expenditure against spare parts availability, technician training, and the ability to expand or reconfigure the system without replacing the entire track infrastructure. In effect, cost competition is moving from unit price to reliability, lead time, and upgrade-option value.
Competitive Landscape and Strategic Positioning
The competitive field combines long-established North American manufacturers with international component suppliers and regional specialists. This mix creates a layered environment where incumbents compete on system breadth, engineering support, and installed-base service, while newer or regional players compete on price, niche load ratings, and localized deployment agility.
PW Consulting
Among the established names, companies with long track records in enclosed track monorail systems emphasize durability, modular installation, and application breadth. Profiles from firms originating in the mid-twentieth century often highlight standardized configurations that simplify specification for auto-body shops, manufacturing floors, and receiving areas. Their differentiation rests on proven uptime narratives, extensive field references, and the ability to offer power-only, power-and-free, and towline variations within a common design language. This breadth allows them to address a wide range of load profiles and throughput requirements while maintaining consistent spare-parts logistics.
Other leading players focus on capacity tiers and integration readiness. Some offer medium-capacity solutions tailored for tight spaces, while others provide heavy-duty variants or over-under configurations designed for large-volume production at a favorable cost position versus traditional I-beam systems. A distinct subset of competitors centers on component-level strength, supplying chains, trolleys, and specialty hardware to system builders and end-users alike. This component-focused model is strategically important because it embeds the supplier within multiple system architectures, creating recurring demand even when full-system projects fluctuate.
Recent activity underscores how competition is shifting toward integration and application-specific demonstrations. Public showcases combining enclosed track conveyors with robotic handling for carton movement and order fulfillment point to a market where mechanical transport is increasingly validated within end-to-end automation scenarios. At the same time, catalog and product updates emphasizing standard components with free-running trolleys for lower-cost overhead applications indicate continued segmentation between value-oriented installations and engineered, higher-capacity systems. The competitive signal is that suppliers are pursuing both ends of the spectrum: premium integration for complex workflows and standardized affordability for simpler overhead transport needs.
Worldwide Enclosed Torque Motor Market
Future Outlook: Trends Shaping the Next Three to Five Years
Several interdependent trends are likely to define market direction through the early 2030s. First, integration depth will increase as facilities seek overhead conveyance that communicates with broader control architectures. This does not necessarily mean every installation becomes highly automated, but it does suggest that compatibility with sensors, programmable logic, and data collection layers will become a more frequent selection criterion. Systems that can be instrumented for throughput monitoring, fault detection, and maintenance scheduling will hold a growing advantage in environments where downtime is costly and changeover frequency is high.
Second, hygiene and contamination control will continue to pull demand toward enclosed configurations in finishing, food-adjacent processing, and clean manufacturing contexts. As environmental and operational standards tighten, the enclosed track's ability to shield chains and trolleys from particulates, overspray, and incidental contamination will be valued not only for equipment longevity but also for process consistency. This trend favors suppliers that can articulate cleaning protocols, material compatibility, and service practices aligned with regulated or high-purity environments.
Third, regional capacity and supplier diversification will likely expand, particularly as end-users seek shorter lead times, localized service, and reduced exposure to single-region supply disruptions. Asia Pacific's substantial revenue presence and the presence of component manufacturers in Taiwan and India indicate an ecosystem capable of supporting both full-system projects and component-level supply. The opportunity for new entrants and expanding incumbents lies in pairing regional manufacturing responsiveness with reliable engineering specifications and compatible interface standards.
Potential risks remain. Steel and motor cost volatility can compress margins and delay projects, especially for engineered systems with long quote-to-delivery cycles. Regulatory updates may raise compliance costs in the near term, particularly for operators retrofitting older installations. In addition, if automation budgets soften in key verticals, procurement may shift toward incremental upgrades rather than full replacement, pressuring suppliers to offer flexible expansion paths and retrofit-compatible components.
Strategic Actions for Decision-Makers
For manufacturers and automation engineers, the priority should be to evaluate enclosed track systems not only on load capacity and footprint, but also on integration readiness, service access, and reconfiguration flexibility. Favor designs that allow span adjustments, trolley interchangeability, and straightforward inspection access, and align component selection with the facility's anticipated product-mix volatility.
For investors and corporate development teams, the opportunity lies in identifying suppliers that combine application breadth with credible service networks and component-level repeatability. Companies that can support multiple verticals while maintaining standardized interfaces and documented compliance practices are better positioned to capture demand as facilities modernize incrementally rather than replacing systems wholesale.
Enclosed Belt Conveyor Market
For procurement and operations leaders, total cost of ownership should be assessed across lead time, spare-parts compatibility, maintenance burden, and upgrade options rather than initial installed price alone. Where hygiene, dust control, or turnover frequency are material, enclosed track configurations warrant explicit comparison against open alternatives, with due attention to compliance documentation and service-response capability. Given the pace of standards updates, integration expectations, and regional supply shifts, more granular segmentation data and tailored scenario analysis can help decision-makers narrow specification choices and time investments more effectively. Readers seeking deeper breakdowns by application profile, regional deployment patterns, and company-level positioning can review the full PW Consulting market report for detailed segmentation metrics and actionable recommendations aligned to specific operational contexts.
For detailed analysis of this topic, please visit the official page: Worldwide Enclosed Track Conveyors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Global Egg Packing Machinery Market: Why Automatic Systems and 5.43% CAGR Redefine Supply Chains
By PW Consulting, 2026-09-18
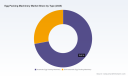
Strategic Trends and Commercial Opportunities in the Worldwide Egg Packing Machinery Market
1. Market Overview and Core Challenges
The global market for egg packing machinery has demonstrated consistent expansion over the past half-decade, with revenue estimates indicating a trajectory from approximately $572.25 million in 2020 to a projected $1.079 billion by 2032. Driven by a compound annual growth rate of 5.43 percent during the 2026-2032 forecast period, the sector reflects a maturation phase where efficiency, hygiene, and scalability dictate procurement decisions rather than mere capacity expansion. The current market size of roughly $745.5 million in 2025 underscores a robust foundation, yet the path forward is not without structural friction. Industry participants must navigate a landscape where volume growth increasingly depends on operational excellence rather than simple market penetration.
One of the most pressing challenges facing the sector is the persistent tension between labor availability and automation requirements. Agricultural and egg processing facilities across multiple regions are grappling with workforce constraints, which directly impact manual grading and packing lines. This labor shortage is not merely a temporary cyclical issue; it represents a structural shift that forces producers to reconsider their reliance on manual processes. The imperative to reduce manual handling and operational costs is accelerating the transition toward automated solutions, yet the capital expenditure required for such transitions can be a barrier for smaller operators who lack the cash flow to invest in high-throughput systems without clear ROI timelines.
Tray Sealing Machines Market
Regulatory pressures form a second critical pivot point. Stringent food safety mandates, particularly those focused on hygiene, Salmonella control, and pasteurization protocols during egg handling, are reshaping equipment specifications. Compliance is no longer optional, and machinery that lacks enhanced sanitary design faces obsolescence risk. Manufacturers and end-users alike must account for these regulatory demands in their capital planning, as retrofitting older lines or investing in new systems with compliant materials—such as stainless steel components for egg contact areas—adds complexity to procurement cycles and total cost of ownership calculations.
A third challenge lies in balancing throughput demands with product integrity. The macro trend of increasing global demand for eggs and processed egg products is pushing facilities to adopt machines capable of handling 10,000 to 60,000 eggs per hour. However, higher speeds must not compromise gentle handling, a requirement that remains paramount for table eggs and breeding stock. Equipment that can deliver both velocity and care is in high demand, but engineering such dual-capability systems requires sophisticated modular designs and precise control systems. Companies that fail to align their product offerings with this balance risk losing ground to competitors who can demonstrate verifiable gentle handling at scale.
2. Key Drivers of Market Growth and Transformation
Technological innovation stands as the primary catalyst reshaping the competitive dynamics of egg packing machinery. Advances in sensor technology, vision systems, and automated sorting algorithms are enabling machines to achieve higher accuracy in grading while minimizing breakage rates. Modular designs have become a hallmark of modern equipment, allowing producers to scale their operations incrementally rather than committing to monolithic line replacements. This flexibility is particularly valuable in an environment where farm sizes and processing volumes can fluctuate due to market conditions, avian influenza outbreaks, or shifting consumer preferences. The ability to integrate fixed or variable speed options, mobile units, and adaptable packing configurations means that machinery can evolve alongside the business, reducing the risk of stranded assets.
The policy and regulatory environment is exerting a profound influence on equipment selection and deployment. Beyond the baseline hygiene and food safety requirements, there is an increasing expectation for traceability and data capture within packing lines. Automated systems that log grading decisions, track egg batches, and integrate with broader farm management software are gaining traction as producers seek to demonstrate compliance and optimize operational insights. Regulations that mandate specific sanitation protocols for wash and packing lines also drive demand for materials and designs that facilitate rapid cleaning and reduce contamination risks. Equipment manufacturers that proactively align their R&D with these regulatory trajectories position themselves as partners in compliance rather than mere vendors of hardware.
On the demand side, consumer and enterprise behavior is shifting in ways that favor processed and value-added egg products alongside traditional table eggs. This diversification requires packing and grading equipment that can handle multiple formats, from standard trays to specialized packaging for liquid egg or further processing. Medium and large farms, as well as dedicated egg processing plants, are increasingly looking for integrated solutions that bridge grading, washing, printing, and packing into a cohesive workflow. The pursuit of throughput efficiency is not solely about volume; it is about consistency, reduced waste, and the ability to meet fluctuating order profiles without sacrificing quality. Enterprises that can demonstrate reliable performance across varied product streams are capturing a larger share of capital expenditure budgets.
PW Consulting
Supply chain and cost structure dynamics also play a pivotal role. The reliance on stainless steel for components in contact with eggs ensures hygiene and durability, but material costs and availability can influence pricing and lead times. Furthermore, the concentration of manufacturing capabilities in certain geographic clusters means that logistics, customs, and local support networks become critical considerations for buyers. Companies that can offer localized service, spare parts availability, and rapid response to downtime minimize the operational risks associated with global procurement. At the same time, cost pressures are driving a search for machines that deliver higher throughput per unit of labor and energy, reinforcing the value proposition of automation even in contexts where labor is available but expensive.
Recent industry activities illustrate how these drivers converge in practice. Participation in major trade exhibitions such as IPPE 2026, which featured extensive exhibits on poultry and egg processing equipment with record attendance and floor space, signals the sector's vitality and the intensity of innovation dissemination. Similarly, manufacturers showcasing their latest grading and packing machines at regional events like CAHE 2026 in Chengdu highlight the growing importance of Asian markets and the desire to demonstrate capabilities directly to a diverse audience of producers and integrators. These events serve as barometers for where technology, demand, and regional growth intersect, offering tangible evidence of the market's directional shifts.
3. Competitive Landscape and Leading Strategies
The competitive environment in egg packing machinery is characterized by a mix of established multinational players and specialized regional manufacturers, with a concentration ratio that suggests a moderately consolidated structure. Leading firms differentiate themselves through a combination of product breadth, technological sophistication, and service ecosystems. Companies that offer automated systems spanning from small farm applications to full-scale production lines with gentle egg handling and modular designs are well-positioned to capture value across diverse customer segments. The ability to provide high-capacity automated packing lines and integrated solutions allows leaders to address the throughput demands of large operations while maintaining the flexibility to adapt to varying egg types and packaging formats.
Strategic positioning among top competitors often hinges on the balance between automation level and operational practicality. Some manufacturers specialize in compact, versatile automatic packing machines that emphasize modularity, mobility, and fixed or variable speed options, catering to facilities that require reliable performance without excessive footprint or complexity. Others focus on gentle egg handling and packing for table eggs in trays, offering both semi-automatic and automated packers suited for layers and breeders. This segmentation of strengths means that buyers must evaluate not only technical specifications but also the alignment of a supplier's core competencies with their own operational profile, growth plans, and regulatory obligations.
Regional diversity among manufacturers adds another layer to the competitive dynamics. Firms based in Europe and North America often emphasize advanced automation, integration with broader poultry systems, and compliance with stringent food safety frameworks, while manufacturers from Asia and other emerging regions frequently compete on cost efficiency, rapid deployment, and complete automated processing and packing lines that cover grading, washing, printing, and separation. This divergence creates opportunities for cross-regional learning and partnership, as well as potential friction in terms of perceived quality, support infrastructure, and long-term reliability. Buyers increasingly weigh total cost of ownership, including service availability and spare parts logistics, against upfront pricing, which can shift the competitive advantage toward suppliers with strong local presence and responsive after-sales networks.
The market is also witnessing evolutionary trends in consolidation and new entry. Larger players with integrated poultry and egg production system portfolios, including egg handling and packing solutions, are well-placed to offer end-to-end value propositions that reduce integration risk for customers. At the same time, specialized firms focusing on egg processing equipment with capabilities supporting packing and sorting lines for food industry applications are carving niches around specific processing needs, such as pasteurization readiness or specialized tray configurations. New entrants and expanding regional players continue to challenge incumbents by targeting underserved segments, leveraging cost structures, and adopting proven technologies to accelerate time-to-market. In this environment, the ability to demonstrate consistent performance, gentle handling, and regulatory compliance becomes a key differentiator, as does the capacity to provide modular, scalable solutions that grow with the customer's business.
The competitive landscape is further shaped by the emphasis on hygiene and material standards. Equipment that prioritizes stainless steel components for egg contact areas not only meets sanitary design expectations but also signals durability and lower long-term maintenance burdens. Suppliers that embed these material choices into their core engineering philosophy, and that can articulate the operational and compliance benefits clearly, build trust with procurement teams that must justify capital investments against both financial and risk-management criteria. The interplay of these factors suggests a market where differentiation is increasingly derived from integrated technology, service reliability, and the ability to navigate the intersection of throughput, hygiene, and flexibility.
4. Future Trends and Strategic Outlook (2026-2032)
One of the most significant trends likely to define the next three to five years is the deepening integration of automation with data-driven management. As labor constraints persist and regulatory scrutiny intensifies, packing lines will increasingly function as nodes within broader digital ecosystems. Grading and packing equipment will be expected to capture granular operational data, support traceability requirements, and interface with farm and processing management platforms. This shift creates commercial opportunities for manufacturers and integrators who can offer seamless connectivity, analytics dashboards, and predictive maintenance capabilities, while also posing a risk for those whose products remain isolated hardware solutions without clear pathways to data integration.
A second trend is the continued push toward higher throughput combined with uncompromising gentle handling. Demand for eggs and processed egg products is expected to remain robust, and facilities will seek machines that can process 10,000 to 60,000 eggs per hour without elevating breakage or compromising hygiene. Innovation in conveyance, cushioning, and speed control will differentiate suppliers, and end-users will reward systems that balance speed with product protection. The opportunity here lies in engineering and marketing solutions that provide verifiable performance metrics, enabling buyers to model ROI based on reduced waste and higher quality output. A risk to monitor is the potential for over-optimization on speed at the expense of handling quality, which can erode trust and lead to costly retrofits or replacements.
Third, regional demand dynamics will continue to reshape where growth is most pronounced and where competitive pressure intensifies. Markets with expanding medium and large farm operations, as well as dedicated processing plants, will drive demand for integrated, high-capacity lines, while smaller or more cost-sensitive regions may favor semi-automatic or modular solutions that allow incremental upgrades. This divergence creates opportunities for tailored go-to-market strategies, localized support models, and product configurations that match regional regulatory and operational contexts. A key uncertainty is the pace of regulatory evolution and the extent to which hygiene and safety mandates accelerate automation adoption across all segments, which could compress the window for semi-automatic solutions in certain markets.
5. Strategic Considerations for Decision-Makers
For manufacturers, the priority is to sustain investment in modular, sanitary, and data-ready designs that can serve a spectrum of farm sizes and processing formats. Aligning R&D with the dual imperatives of throughput and gentle handling, while ensuring compliance with evolving hygiene standards, will strengthen competitive positioning. Building robust service and parts networks, along with clear communication of material choices such as stainless steel for critical components, can differentiate offerings in a market where total cost of ownership matters as much as initial price.
High Speed Packaging Machine Market
For investors, the landscape suggests selective opportunities in companies that demonstrate scalable technology platforms, strong regional presence, and the ability to integrate packing solutions with broader poultry system portfolios. Concentration dynamics indicate that consolidation and partnership activity may continue, and due diligence should weigh service capabilities, regulatory alignment, and the flexibility of product lines to adapt to shifting demand patterns. Tracking exhibition activity and product launches at major industry events can provide early signals of innovation direction and regional focus.
For purchasers and procurement teams, the decision matrix should extend beyond headline throughput figures. Evaluating gentle handling performance, hygiene design, modularity, and the supplier's ability to support compliance and data integration will reduce long-term operational risk. Engaging with suppliers that can demonstrate reliable performance across varied product streams, and that offer clear pathways for incremental capacity expansion, helps balance immediate needs with future growth. For those seeking granular segmentation data and tailored strategic recommendations, the full research report provides detailed breakdowns across regions, types, and applications, along with scenario analysis to support capital planning and competitive positioning.
For detailed analysis of this topic, please visit the official page: Worldwide Egg Packing Machinery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Printing Plate Market 2026: Packaging Demand Drives 2.82% CAGR Beyond Forecasts
By PW Consulting, 2026-09-18
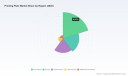
The Worldwide Printing Plate Market: Strategic Trends and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
The global printing plate market has navigated a period of recalibration, evolving from a stable growth trajectory into a landscape defined by structural shifts and margin pressures. With a compound annual growth rate of 2.82% projected through 2032, the sector is not experiencing explosive expansion but rather a mature, value-driven evolution. Revenue figures have demonstrated resilience, climbing from approximately $4.15 billion in 2020 to a base-year valuation of $4.78 billion in 2025. This trajectory reflects an industry that has absorbed significant external shocks while maintaining its foundational role in global printing infrastructure. However, the path forward is anything but linear, and stakeholders must look beyond headline metrics to understand the underlying dynamics.
One of the most pressing challenges confronting the industry is the volatility in raw material costs, particularly aluminum. The primary substrate for conventional offset and lithographic printing plates has seen sustained price escalation, with the US Producer Price Index for aluminum sheet, plate, and foil manufacturing reaching 221.71 in early 2025, marking a year-over-year increase of over twelve percent. This cost pressure is not isolated; it directly translates into pricing power struggles across the value chain. Suppliers are forced to pass through increases, while converters and end-users resist, creating a tense negotiation environment that compresses margins and demands operational agility. Companies that rely heavily on traditional aluminum-based plates are finding that input cost management is no longer a back-office function but a strategic imperative.
A second critical challenge lies in the regulatory environment, which is rapidly reshaping responsibility and cost allocation. As of 2025, multiple US states have enacted Extended Producer Responsibility laws that explicitly cover packaging materials and printed paper. These regulations shift the financial and operational burden of end-of-life management from municipal systems to producers, compelling them to account for the environmental footprint of their packaging choices. This regulatory wave is not merely a compliance exercise; it fundamentally alters the value proposition of packaging materials and the printing plates that enable them. Manufacturers must now consider how plate technology influences substrate recyclability, waste generation, and the overall sustainability narrative that downstream brands are increasingly required to communicate.
Digital Offset Printing Plate Market
Market concentration further complicates the landscape. The sector is characterized by a moderately consolidated structure, where a relatively small group of dominant players captures a substantial share of revenue. This concentration provides scale advantages in R&D and global distribution but can also create barriers for niche innovators and regional players. The interplay between entrenched incumbents and agile specialists creates a dynamic where differentiation is increasingly tied to technological specificity rather than broad market presence. Understanding this concentration dynamic is essential for assessing competitive threats and partnership opportunities.
The industry stands at a crossroads where cost pressures, regulatory mandates, and concentration dynamics intersect. Navigating this environment requires more than incremental adjustments; it demands a clear-eyed assessment of which structural forces are temporary and which represent permanent shifts in how printing plates are sourced, produced, and valued.
Key Drivers of Market Evolution
Technological innovation continues to serve as the primary engine of differentiation in the printing plate market, with sustainability and process efficiency converging into a single strategic priority. Developments such as process-free and pre-heat-free offset plates, alongside chem-free technologies, reflect a broader industry push to reduce chemical consumption, lower energy requirements, and simplify plate processing workflows. These innovations are not merely incremental improvements; they address operational pain points that directly impact total cost of ownership for print service providers. By eliminating or reducing wet processing steps, manufacturers are enabling faster turnaround times, lower water usage, and reduced hazardous waste handling, all of which resonate with both economic and environmental objectives. The integration of renewable raw materials into polymer layers, with some recent flexographic plate series incorporating upwards of nineteen to twenty-nine percent bio-based content, further illustrates how material science is being leveraged to meet sustainability targets without sacrificing print quality or run length performance.
Policy and regulatory frameworks are acting as powerful accelerants for technology adoption and supply chain reconfiguration. Extended Producer Responsibility laws, now active in multiple jurisdictions, are forcing a reevaluation of packaging lifecycles and the role of printing substrates within them. For plate manufacturers, this regulatory shift has two implications. First, it creates demand for plates that enable cleaner, more recyclable packaging outputs, particularly in flexographic and offset applications where ink adhesion, substrate compatibility, and waste reduction are critical. Second, it introduces compliance complexity that rewards companies with strong regulatory intelligence and the ability to provide documented sustainability credentials. The requirement for producers to register with designated responsibility organizations and report on material flows means that transparency and traceability are becoming competitive differentiators, not just operational niceties.
Demand-side behavior is undergoing a parallel transformation, driven by shifts in consumer preferences and enterprise procurement strategies. The continued global expansion of e-commerce and the premium placed on high-quality flexible packaging have reinforced demand for flexographic plates optimized for corrugated and film-based substrates. At the same time, commercial printers are increasingly consolidating their plate sourcing around suppliers that offer predictable performance, shorter makeready times, and consistent color fidelity. This behavior is pushing the market toward solutions that reduce variability and improve throughput, particularly in high-volume packaging runs where downtime and waste carry significant financial consequences. Brands are also becoming more vocal about the environmental attributes of their packaging, which cascades pressure down to converters and plate suppliers to demonstrate measurable sustainability gains.
Supply chain and cost structure dynamics are reshaping competitive positioning in ways that extend beyond raw material pricing. The sustained elevation of aluminum costs has forced a reevaluation of substrate alternatives, processing efficiencies, and pricing architectures. Suppliers that can decouple performance from pure aluminum dependence, whether through hybrid material designs, thinner gauge plates, or alternative substrate chemistries, gain a structural advantage. Simultaneously, the integration of digital workflow tools that optimize plate imposition, reduce waste, and improve press readiness is becoming a critical component of value delivery. The ability to offer end-to-end efficiency, rather than a commodity plate, is increasingly what separates long-term partners from transactional vendors. These drivers collectively point toward a market where value is created not through volume alone but through technological specificity, regulatory alignment, and total cost optimization.
Competitive Landscape and Leading Strategies
The competitive field in the printing plate market is defined by a mix of global specialists, diversified material science players, and focused regional manufacturers, each pursuing distinct strategic positioning. Fujifilm Holdings Corporation has built a reputation around thermal and violet CTP plates, including process-free and Brillia series offerings, which aligns with the market's push toward reduced chemical use and workflow simplification. Agfa-Gevaert, operating through its ECO3 brand, has emphasized chem-free and pre-heat-free offset technologies such as the Azura and Energy Elite series, targeting both commercial and packaging segments with a clear sustainability narrative. These players illustrate a common strategy among leading incumbents: leverage process innovation to reduce total operating costs for customers while building a defensible sustainability proposition.
Flexographic plate specialists occupy a different competitive tier, driven by the structural growth of flexible packaging and labeling. Flint Group, with its Nyloflex portfolio and consumables focus, competes on depth of application expertise in flexible packaging and labels. DuPont, MacDermid Graphics Solutions, and Miraclon, through its FLEXCEL technology, each pursue differentiated photopolymer and flexographic solutions optimized for specific substrate performance and impression requirements. Asahi Photoproducts has carved out a position with water-washable flexographic plates that address environmental processing concerns, while Toray and Toyobo focus on high-run flexographic plates and photopolymer solutions tailored to packaging durability and consistency. XSYS rounds out this competitive group with Nyloflex and Nyloprint offerings that serve both flexographic and letterpress applications in packaging. These companies share a common strategic thread: deep application specificity, close collaboration with converters and brand owners, and continuous iteration on polymer formulations and plate handling characteristics.
Several other players bring distinct advantages to the competitive mix. Eastman Kodak Company continues to leverage process-free thermal photopolymer plates for offset and packaging, drawing on established brand recognition and technology heritage. Heidelberger Druckmaschinen AG provides offset plates and integrated systems that align with sheetfed and packaging production workflows. PlateCrafters and Container Graphics Corporation represent a more specialized tier, manufacturing custom flexographic photopolymer plates for corrugated and packaging applications, often competing on responsiveness, customization, and niche substrate expertise. The presence of these focused manufacturers highlights a market where segmentation is not just about plate type but about application tuning, regional service density, and the ability to address specific substrate challenges.
Recent market developments provide concrete evidence of how these competitive dynamics are playing out. In February 2026, ECO3 announced a double-digit global price increase for offset printing plates, citing continued rises in aluminum costs and aluminum-related treatments, with the adjustment taking effect in March 2026. This move underscores the pricing pressure that raw material volatility places on suppliers and signals that cost pass-through is becoming a more frequent competitive lever. Conversely, in May 2025, XSYS launched the Nyloflex Eco Flexo Plate Series, incorporating a notable share of renewable raw materials in the polymer layer while reducing processing time for packaging applications. This launch illustrates how competitors are using material innovation and process efficiency to differentiate beyond price, targeting customers who value sustainability credentials and workflow improvements in equal measure.
The market structure is evolving along two parallel tracks. On one hand, consolidation pressures remain, as larger players with global distribution, integrated R&D, and diversified product portfolios are well-positioned to capture share from smaller, less-resourced competitors. On the other hand, fragmentation persists in application-specific niches, where specialized plate formulations, regional service capabilities, and custom product development create opportunities for focused players to thrive. New entrants or expanders that bring meaningful technological differentiation, strong sustainability credentials, or superior cost structures can disrupt established relationships, particularly in packaging segments where brand owner mandates are reshaping converter preferences. The net effect is a landscape where competitive advantage is increasingly tied to the ability to combine material innovation, regulatory responsiveness, and total cost optimization rather than scale alone.
Future Trends and Commercial Implications
Looking toward the 2026 to 2032 horizon, three interconnected trends are likely to shape the direction of the printing plate market. First, sustainability-driven material innovation will move from a differentiator to a baseline expectation, particularly in packaging applications. Plates that incorporate renewable content, reduce processing chemical requirements, or enable lower-waste press runs will increasingly be evaluated alongside traditional performance metrics. This trend creates commercial opportunity for suppliers that can document measurable environmental benefits without compromising print quality, run length, or press compatibility. It also raises the bar for competitors that continue to rely on conventional material architectures, as regulatory mandates and brand owner procurement criteria tighten.
Second, pricing dynamics and cost structure adaptation will remain central to competitive strategy. With aluminum costs elevated and regulatory requirements adding new layers of operational expense, the ability to manage input costs, optimize plate thickness, and deliver workflow efficiencies will differentiate financially resilient players from those squeezed by margin compression. Companies that invest in substrate alternatives, process simplifications, and digital workflow integration are positioned to offer more predictable total cost profiles, which is increasingly valuable to converters operating under tight margins and volatile input markets. The trend suggests a market where pricing power will belong to those who can articulate and deliver tangible cost advantages across the full production lifecycle.
Third, regulatory expansion and producer responsibility frameworks will continue to reshape procurement behavior and product specifications. As more jurisdictions implement Extended Producer Responsibility requirements and packaging waste targets, the printing plate market will feel indirect but meaningful pressure to align with downstream sustainability goals. This creates opportunities for suppliers that can provide compliance-supporting documentation, lifecycle transparency, and plate technologies that facilitate recyclability or waste reduction. However, it also introduces risk for players that lack regulatory visibility or whose product portfolios are heavily tied to substrates and processes that may face future restrictions or cost penalties.
These trends converge on a clear commercial implication: value will migrate toward solutions that combine performance, sustainability, and cost predictability. Suppliers and investors who anticipate these shifts and align their portfolios accordingly will be better positioned to capture growth in packaging and commercial segments where these factors are becoming decisive. The primary uncertainty lies in the pace and geographic scope of regulatory adoption, as well as the extent to which raw material costs stabilize or continue their upward trajectory. Both variables will influence the speed at which sustainability and cost innovations translate into market share gains.
Actionable Recommendations for Decision-Makers
For plate manufacturers and technology suppliers, the priority is to accelerate investment in process-efficient and material-innovative plate solutions that directly address sustainability mandates and cost pressures. Differentiation should focus on measurable reductions in chemical use, processing time, and waste, paired with clear documentation that supports customer compliance and brand owner sustainability claims. Strategic partnerships with converters and packaging producers can provide early feedback loops and co-development opportunities that lock in preference before procurement criteria harden.
For investors evaluating exposure to this market, the opportunity lies in companies that demonstrate a credible path to total cost leadership and regulatory alignment, rather than those competing solely on scale or legacy product breadth. Attention should be paid to players with strong flexographic and packaging specialization, as these segments are benefiting from structural demand growth and brand owner sustainability mandates. Monitoring raw material cost trajectories, regional regulatory expansion, and M&A activity among mid-tier specialists will provide early signals of shifting competitive dynamics and valuation opportunities.
For procurement leaders and print service providers, the strategic imperative is to evaluate plate suppliers based on total cost of ownership, process reliability, and sustainability support, rather than unit price alone. Engaging suppliers early in packaging design and workflow planning can unlock makeready efficiencies, reduce waste, and improve press consistency, all of which contribute to margin protection in a cost-volatile environment. Building supplier relationships that include regulatory intelligence and sustainability documentation will also reduce compliance risk and strengthen brand owner confidence.
Flexographic Printing Plate Market
As the market evolves, the leaders who capture disproportionate value will be those with access to granular segmentation data, company-level competitive benchmarks, and forward-looking scenario analysis that ties regulatory, cost, and technology trajectories to specific commercial outcomes. A detailed research report can provide the segmentation-level revenue breakdowns, regional demand patterns, product-level performance comparisons, and customized strategic recommendations needed to translate these macro trends into precise action plans. Access to this level of depth enables decision-makers to move from general awareness to targeted portfolio adjustments, pricing strategies, and partnership decisions that directly impact competitiveness through 2032.
PW Consulting
For detailed analysis of this topic, please visit the official page: Worldwide Printing Plate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
CLD NOx Analyzer Market: Why 4.96% CAGR and Regional Shifts Redefine Growth Basins
By PW Consulting, 2026-09-18
Global CLD NOx Analyzer Market: Strategic Trends, Competitive Dynamics, and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
The worldwide market for chemiluminescence detection (CLD) nitrogen oxide analyzers has demonstrated resilient expansion over the past half-decade, reaching approximately USD 524.45 million in 2025. Following a period of moderate volatility between 2020 and 2023, the sector has stabilized and resumed a steady upward trajectory, with sales spanning USD 420.15 million in 2020 to the current baseline. Projections indicate continued growth through the forecast horizon, with revenues expected to approach USD 735.84 million by 2032, reflecting a compound annual growth rate of 4.96 percent. This expansion is not merely a function of incremental demand; it reflects the deepening integration of precision emission monitoring into regulatory compliance, industrial operations, and environmental stewardship frameworks across multiple geographies.
Despite the constructive demand backdrop, the CLD NOx analyzer market faces structural friction points that will shape competitive outcomes in the near term. The first challenge lies in balancing measurement sensitivity with operational robustness. Modern environmental and industrial mandates increasingly require detection at parts-per-billion and even parts-per-trillion levels, yet field-deployed systems must withstand harsh exhaust conditions, temperature fluctuations, and particulate-laden gas streams. Manufacturers that cannot reconcile laboratory-grade precision with ruggedized, low-maintenance field performance risk losing share to alternative sensing approaches or to competitors who have successfully engineered hybrid architectures.
A second tension emerges from the evolving regulatory patchwork. Compliance frameworks are tightening globally, but they do so at different speeds, with differing certification pathways, and often with ambiguous alignment between ambient air quality monitoring standards and continuous emissions monitoring requirements. Organizations deploying or procuring CLD systems must navigate overlapping validation protocols, which increases integration costs, extends qualification timelines, and complicates multi-region product strategies. The result is a market where regulatory alignment is as commercially important as raw instrument performance.
The third challenge is market concentration and its implications for pricing, innovation cadence, and customer leverage. A relatively small group of established players accounts for a substantial portion of total sales, while the remaining market is distributed across specialized and regional suppliers. High concentration can stabilize pricing and accelerate technology diffusion through well-resourced R&D programs, but it can also raise barriers to entry for new innovators and constrain buyer flexibility. Procurement teams seeking multiple sourcing options, or smaller laboratories requiring cost-efficient configurations, often encounter limited alternatives outside the dominant tiers. This dynamic is gradually pressuring incumbents to demonstrate clear total-cost-of-ownership advantages and to offer modular, application-tailored solutions rather than relying solely on generalized flagship models.
Taken together, these challenges create a market that rewards technical credibility, regulatory fluency, and deployment flexibility. Companies and buyers that understand where the friction points sit can position themselves more effectively, whether by investing in hardened measurement platforms, aligning products with specific certification regimes, or structuring procurement to manage supply concentration risk. The remainder of this analysis examines the forces currently reshaping demand and competitive positioning, followed by forward-looking implications for strategy and investment.
Key Drivers of Market Change
Technological Innovation and the Push Toward Lower Detection Limits
The most visible driver of growth in the CLD NOx analyzer market is the ongoing refinement of chemiluminescence detection architecture itself. Traditional photomultiplier tube-based designs remain widely deployed, but there is a meaningful shift toward solid-state detection elements and heated-flow configurations that improve signal stability, reduce warm-up times, and extend service intervals. These advances matter because the practical value of a NOx analyzer is no longer determined solely by its specified detection threshold; it is increasingly judged by how reliably that threshold is maintained under real-world sampling conditions.
Ozone Analyzer Market
Recent exhibition activity and product demonstrations highlight this trajectory. In May 2025, ECO PHYSICS showcased its chemiluminescence NOx analyzers at the EPRI CEMUG 2025 event in Atlanta, reinforcing the industry’s focus on continuous emissions monitoring applications where robust field performance and traceability are paramount. Such appearances are not merely promotional; they signal where engineering attention and customer interest are converging. Manufacturers are investing in instruments that combine low-level measurement capability with practical operational features, such as improved ozone generation control, minimized optical drift, and software-assisted calibration workflows.
For buyers, this innovation cycle changes the evaluation criteria. The most competitive instruments increasingly distinguish themselves through measurement repeatability across long deployment cycles, ease of integration into existing monitoring networks, and transparency in validation documentation. For manufacturers, the strategic implication is clear: incremental sensitivity improvements alone are insufficient. The next layer of differentiation belongs to systems that reduce downtime, simplify compliance reporting, and maintain accuracy in demanding combustion and stack environments.
Regulatory Pressure and Standardization as Demand Catalysts
Policy and regulatory evolution remains a foundational demand driver. The chemiluminescence method continues to be embedded in widely recognized testing and monitoring protocols, reinforcing its position in both ambient air quality networks and industrial emissions applications. In the United States, reference methods and audit procedures applicable to chemiluminescent NOx analyzers continue to shape procurement specifications, particularly for facilities subject to routine relative accuracy evaluations and emissions compliance reporting.
In Europe and the UK, certification pathways under quality assurance frameworks for continuous emissions monitoring and ambient monitoring networks remain central to procurement decisions. The establishment of updated European standards specifying requirements for the selection, installation, and operation of chemiluminescence NOx analyzers in air quality monitoring networks underscores the sector’s shift from generic performance claims toward documented, auditable deployment practices. These standards matter commercially because they influence not only which instruments can be used, but also how implementation is scoped, validated, and maintained over time.
This regulatory environment creates a dual effect. First, it sustains baseline demand from compliance-driven buyers who must meet defined monitoring obligations. Second, it raises the value of instruments and service packages that reduce the administrative and technical burden of certification maintenance. Suppliers that can provide clear alignment with recognized methods, along with practical support for audit readiness and network integration, are better positioned to convert regulatory pressure into durable contract value.
Demand-Side Shifts Across Automotive, Industrial, and Environmental Monitoring
Demand patterns are being reshaped by changes in how combustion emissions are tested, how industrial stacks are monitored, and how ambient air quality networks are designed. In automotive emission testing, the emphasis on real-time, high-sensitivity measurement of NO and NOx continues to support heated analyzer configurations that perform reliably under dynamic sampling conditions. This application area benefits from both regulatory oversight and engineering demand for precise combustion diagnostics, making it one of the more consistently active segments of the market.
Industrial stack monitoring represents another major demand center. Facilities operating combustion processes, turbines, boilers, and related equipment increasingly treat continuous emissions data not simply as a compliance obligation but as a source of operational insight. When NOx measurement is integrated into plant performance monitoring and combustion optimization workflows, the analyzer becomes part of a broader efficiency and risk-management system rather than a standalone compliance instrument. This shift expands the value proposition of CLD technology beyond regulatory minima and into operational decision support.
Ambient air quality monitoring and research applications form a third demand vector, though with a different purchasing profile. In these settings, measurement accuracy, certification status, and network compatibility often carry more weight than high-throughput industrial durability. The research and laboratory segment, while smaller in absolute terms, plays an outsized role in validating new measurement approaches and in training procurement and operations teams on best practices for low-level NOx detection. Across these demand centers, a common thread is the desire for instruments that can credibly support both compliance and analytical rigor without requiring excessive maintenance burden.
Supply Chain, Cost Structure, and the Practical Economics of Ownership
A fourth driver shaping the market is the underlying cost structure of CLD instruments and the practical economics of ownership. These analyzers depend on specialized components such as light detection elements and internal ozone generation subsystems, which influence both performance and service requirements. Because the chemiluminescence reaction relies on controlled ozone production and stable optical detection, variations in component quality, calibration gas management, and maintenance scheduling can materially affect total cost of ownership.
As a result, cost competition in this market rarely plays out as a simple instrument price war. More often, it unfolds through service contracts, calibration support, component lifecycle planning, and software-enabled maintenance scheduling. Buyers are increasingly attentive to whether a supplier can provide predictable uptime, manageable consumable costs, and rapid resolution of field issues. Suppliers, in turn, are incentivized to design instruments that reduce sensitivity to component drift, standardize service procedures, and offer configurable configurations aligned with specific application profiles. This dynamic is gradually tilting the competitive battleground toward reliability engineering and commercial flexibility, not just nominal measurement specifications.
Combustion Analyzer Market
Competitive Landscape and Leading Strategies
The CLD NOx analyzer market is characterized by a set of established, technically credible manufacturers that compete across overlapping application areas while maintaining distinct strategic emphasis. ABB occupies a strong position through instruments built around solid-state chemiluminescence detection for low and ultra-low NOx measurement in combustion applications and continuous emissions monitoring. Its positioning reflects a focus on next-generation detection elements and on meeting the precision demands of modern combustion diagnostics and compliance monitoring. For customers, this translates into a value proposition centered on measurement stability at low concentration levels and on integration with combustion and emissions workflows.
HORIBA competes with a strong emphasis on heated-type CLD configurations, particularly for high-sensitivity real-time measurement of nitrogen oxide species in emissions testing. Its approach is closely aligned with applications where temperature management and rapid response are essential to sample integrity. In practice, HORIBA’s differentiation rests on instrument architectures that prioritize measurement fidelity under dynamic sampling conditions, which is especially relevant for vehicle and engine testing environments where transient emissions behavior must be captured accurately.
Servomex, as part of Spectris, supplies analyzer systems that apply the chemiluminescence method to NO, NO2, and NOx measurement across emissions monitoring, engine testing, and process applications. Its commercial strength is reinforced by alignment with widely recognized testing standards and by a reputation for measurement consistency in regulated environments. This positions Servomex as a trusted option for buyers who need instruments that can withstand scrutiny under formal compliance frameworks and integrate into both continuous monitoring and test-cell operations.
ENVEA addresses a distinct portion of the market through instruments designed for ambient air monitoring and continuous emissions monitoring, with certification status that supports deployment in regulated monitoring networks. Its portfolio reflects an emphasis on suitability for air quality networks and for ongoing emissions measurement, supported by recognized quality assurance alignment. This dual applicability is strategically useful because it allows the company to serve both environmental monitoring authorities and industrial customers who require credible, validated measurement across different operating contexts.
California Analytical Instruments contributes a strong field-oriented offering through heated CLD configurations intended for gas sample analysis in NO, NOx, and NO2 applications. Its 700 series emphasis on heated models signals a practical orientation toward demanding sample environments where temperature control helps preserve measurement accuracy. This positions CAI as a relevant supplier for customers focused on robust field deployment and straightforward integration into gas analysis setups that must handle variable and challenging sample conditions.
ECO PHYSICS distinguishes itself through high-performance CLD instruments spanning both compliance-focused and scientific use cases. Its product range includes analyzers designed for continuous emissions monitoring and trace-level measurement in laboratory settings, reflecting an ability to serve customers who require extreme sensitivity alongside operational compliance. This breadth is strategically important because it allows the company to address both regulated field monitoring and high-precision research demand, two segments that increasingly value instruments capable of bridging measurement rigor with practical deployment demands.
Teledyne API offers chemiluminescence analyzers for ambient and dilution-based continuous emissions monitoring, supported by software tools designed to aid data management and operational oversight. Its approach highlights the growing importance of software-assisted monitoring workflows, where instrument performance is complemented by usability features that simplify data handling and configuration management. In environments where monitoring networks must be operated efficiently and maintained consistently, this combination of measurement hardware and operational software can be a meaningful differentiator.
Signal Group rounds out this competitive field with heated vacuum chemiluminescence analyzers aimed at emissions monitoring, combustion studies, and process applications. Its emphasis on vacuum-based chemiluminescence architecture reflects a technical positioning oriented toward measurement sensitivity and controlled reaction environments. For customers involved in combustion research and emissions characterization, this positioning offers an alternative technical route within the broader CLD landscape.
Taken together, these players illustrate a market in which differentiation is increasingly multidimensional. Leadership no longer depends on a single performance claim; it depends on how effectively a company aligns detection technology, certification compatibility, service economics, and application-specific engineering. Looking forward, the competitive landscape is likely to evolve along three lines. First, consolidation and portfolio breadth may become more valuable as buyers seek suppliers that can support multiple monitoring contexts without fragmenting their compliance and maintenance responsibilities. Second, specialization will remain important for companies that address niche requirements such as ultra-trace laboratory measurement or highly ruggedized field configurations. Third, new entrants and alternative sensing approaches will continue to exert pressure at the margins, especially where buyers are willing to trade some measurement tradition for lower cost or simpler deployment. The likely outcome is a market where incumbents maintain strength through credible differentiation and service ecosystems, while competitive pressure steadily improves the quality, transparency, and usability of CLD-based monitoring solutions.
Future Trends and Commercial Implications
One of the most consequential trends for the next three to five years is the continued migration from compliance-only monitoring toward measurement systems that also support operational optimization. As industrial operators and testing organizations become more comfortable using NOx data for combustion tuning, process diagnostics, and emissions strategy planning, demand will increasingly favor instruments that deliver stable, integrated data streams rather than isolated periodic readings. This creates commercial opportunity for suppliers that can package measurement hardware with software-enabled workflows, standardized data handling, and practical integration support. The risk is that buyers may begin to compare CLD systems not only on analytical performance but also on their ability to reduce operational overhead, which raises the stakes for service design and lifecycle economics.
PW Consulting
A second trend is the growing importance of multi-context compliance readiness. As regulatory expectations continue to tighten across regions and application types, instruments and monitoring packages that can demonstrate alignment with recognized methods and certification pathways will enjoy stronger procurement positioning. This favors suppliers that invest in documentation, validation support, and deployment guidance, especially for buyers managing monitoring networks across multiple sites or jurisdictions. At the same time, the unpredictability of regulatory pacing introduces uncertainty. If standards evolve unevenly or if audit expectations shift, companies that have over-indexed on a narrow compliance assumption may face rework costs, while more flexible architectures may gain advantage.
A third trend concerns the balance between sensitivity and field robustness. Demand for lower detection limits will persist, particularly in ambient monitoring and research, but the practical winner in broader commercial deployments will be the solution that maintains that sensitivity with manageable maintenance and stable long-term performance. This trend creates opportunities for instrument designs that reduce optical drift, streamline calibration management, and improve resilience in challenging sample environments. The associated risk is that overly ambitious sensitivity claims, if not matched by serviceable field performance, can erode trust and open space for alternative measurement approaches where appropriate. For investors and manufacturers, the strategic implication is to prioritize demonstrated reliability and integration value alongside analytical specifications, because those are likely to determine repeat purchasing and long-term customer retention.
Strategic Recommendations for Decision-Makers
For manufacturers, the priority should be to strengthen total-value positioning rather than competing exclusively on nominal detection capability. That means investing in configurations that address real deployment pain points: maintenance predictability, calibration and audit readiness, software-supported data workflows, and application-specific robustness. Companies that can map their instruments clearly to recognized compliance contexts while also demonstrating operational convenience will be better positioned to defend pricing and expand share in both emissions monitoring and testing markets. It is equally important to monitor where regulatory alignment is becoming more demanding, because products that are designed with certification and documentation discipline from the outset will scale more easily across regions and customer segments.
For investors, the most informative signals are not headline revenue figures alone but the direction of product architecture, service economics, and regulatory alignment. Instruments and suppliers that combine credible measurement performance with defensible service models and software-supported operation are more likely to sustain demand through compliance cycles and operational adoption. Attention should also be paid to segments where monitoring is shifting from a pure obligation to an operational tool, because that transition expands the addressable value of CLD-based measurement. Conversely, caution is warranted where pricing pressure is being addressed through component compromise or where product claims are not matched by support infrastructure, since those conditions can undercut long-term competitiveness.
For procurement and operations leaders, the practical goal is to evaluate CLD NOx analyzers as part of a broader monitoring and compliance strategy rather than as isolated instrument purchases. Evaluation criteria should include certification status, compatibility with applicable methods, expected maintenance burden, service responsiveness, and the degree to which the instrument can integrate with existing data and reporting workflows. Where monitoring networks span multiple sites or jurisdictions, flexibility in configuration and clarity in validation documentation can reduce implementation risk. Buyers should also consider whether a supplier’s offering supports the intended balance between compliance assurance and operational insight, because that balance increasingly shapes the long-term value of the investment.
For organizations seeking to move from general market awareness to detailed segment-level decisions, a focused examination of regional demand patterns, application-specific sizing, competitive positioning by product family, and the commercial implications of certification and service economics can materially improve planning quality. Detailed breakdowns of segmentation, supplier share dynamics, and application-driven procurement criteria provide the granularity needed to translate these strategic themes into procurement specifications, product roadmaps, and investment theses.
For detailed analysis of this topic, please visit the official page: Worldwide CLD NOx Analyzer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Fine Surface Oriented Strand Board FOSB Market: Why 5.85% CAGR Through 2032 Changes Everything
By PW Consulting, 2026-09-18
Fine Surface Oriented Strand Board (FOSB) Market: Navigating Strategic Trends and Commercial Opportunities
Market Overview and Core Challenges
The Fine Surface Oriented Strand Board (FOSB) market has established itself as a significant segment within the broader wood-based panels industry, bridging the performance characteristics of traditional Oriented Strand Board (OSB) with the aesthetic and surface quality requirements of finer applications. Over the historical period from 2020 to 2025, the market demonstrated resilient growth, reflecting steady commercialization and increasing adoption across multiple downstream sectors. With the value expanding from approximately 939.85 million USD to 1250.0 Million in 2025, the sector has transitioned from a niche product to a recognized alternative to plywood, medium-density fiberboard (MDF), and particleboard in specific use cases. Projections for the forecast period 2026 through 2032 indicate sustained expansion, driven by broader structural demand for engineered wood products and the material's favorable strength-to-weight properties.
At the macroeconomic level, the market is characterized by a moderate consolidated structure. The top three firms hold a combined share of roughly 28.5 percent, while the top five account for about 39.2 percent of total revenue. This concentration suggests that while global capacity is distributed across multiple geographies, specialized FOSB production is still dominated by a limited number of players with the technical capability to produce fine surface layers at commercial scale. The forecast compound annual growth rate of approximately 5.85 percent through 2032 points to steady but not explosive expansion, implying that value creation will increasingly depend on differentiation, cost efficiency, and alignment with downstream application trends rather than pure volume scaling.
Despite the positive trajectory, the industry currently faces several structural challenges that are shaping competitive positioning. First, raw material security and adhesive cost exposure remain persistent concerns. FOSB production relies on specific feedstock profiles, often fast-growing eucalyptus or selected softwood strands, combined with resin systems that meet stringent surface and emission requirements. Fluctuations in wood supply dynamics and the cost of adhesives, which are influenced by petrochemical feedstock movements, introduce margin variability that producers cannot entirely pass through to downstream buyers.
Second, the market sits at a technical crossover point. FOSB must continuously justify its position against established substitutes such as MDF and high-grade particleboard, particularly in furniture manufacturing and interior finishing, where surface finish, machining behavior, and total installed cost are tightly evaluated. While FOSB offers structural advantages and surface quality improvements over standard OSB, the value proposition must be clearly articulated to specifiers and fabricators who are accustomed to traditional materials.
Third, regulatory and environmental expectations are becoming more granular across major end markets. Low formaldehyde emission classifications and other indoor air quality considerations are increasingly treated as baseline requirements rather than differentiators, especially in furniture and interior construction applications. Compliance is necessary, but it also compresses the space for premium pricing unless accompanied by genuine performance or process advantages.
Key Drivers Shaping the FOSB Market
The growth and evolution of the FOSB market are being shaped by a convergence of technological, regulatory, demand-side, and cost-structure developments. Understanding how these forces interact is essential for identifying where durable advantages can be built.
Technology and process capability remain the most distinctive driver. FOSB is not simply OSB with a cosmetic overlay; it typically integrates an OSB core with fine surface layers engineered for superior finish and structural properties. Producers investing in advanced continuous press technology and precision surface treatment are better positioned to deliver consistent panel quality, reduced variability, and surface characteristics that can compete with more traditionally processed boards. The move toward low-formaldehyde or formaldehyde-free adhesive solutions in selected product lines further illustrates how process innovation can simultaneously address performance, regulatory, and branding objectives. Where these technologies are deployed effectively, they enable FOSB to enter applications that previously favored MDF or laminated particleboard.
On the policy and regulatory side, emission standards and interior-use specifications are acting as both a constraint and an enabler. Low formaldehyde emission grades, such as E0 and E1 classifications, have become standard expectations in major markets for FOSB used in furniture and interior applications. Rather than being treated as optional premium features, these requirements are increasingly embedded in procurement specifications and building practices. This regulatory trajectory favors producers that have already integrated cleaner adhesive systems and quality control processes into their operations, while creating a barrier for capacity that cannot reliably meet tighter emission profiles at scale.
Demand-side dynamics are equally important and are shifting the center of gravity for FOSB adoption. Furniture manufacturing continues to represent a large end-use segment, where surface appearance, stability, and finish compatibility influence material selection. At the same time, construction and renovation activity sustains demand for panels that combine structural performance with improved surface qualities for exposed or semi-exposed applications. A smaller but meaningful portion of demand also comes from packaging and industrial uses, where board consistency and mechanical properties matter. What ties these segments together is a broader move toward engineered wood solutions that can reduce weight, improve dimensional stability, or offer more predictable machining behavior than conventional alternatives.
Cost structure and supply chain factors complete the picture. Wood-based panel economics are sensitive to feedstock availability, log and fiber pricing, energy costs, and resin markets. For FOSB, the use of fast-growing eucalyptus or selected softwood strands and the incorporation of specialized adhesives mean that procurement strategy is tightly linked to product positioning. Recent price signals for OSB and FOSB in key supply regions indicate a market where cost discipline matters, but where differentiation in surface quality and adhesive profile can still support value-based positioning. Producers that manage feedstock mix, press efficiency, and resin usage with greater precision are better insulated against input volatility and more capable of competing on quality rather than price alone.
Competitive Landscape and Leading Strategies
The competitive environment in FOSB is defined by a mix of established OSB producers, regional specialists, and manufacturers actively expanding fine-surface capability. The strategic positioning of leading firms reflects different combinations of technology access, feedstock strategy, geographic presence, and application focus.
Strategic Positioning Among Core Players
PW Consulting Health Care Research Center
Fletcher Building is advancing a focused FOSB strategy that emphasizes the material's superiority over particleboard and MDF in targeted applications. Its planned CEBRO Fine OSB production at the Laminex Taupo site, supported by Dieffenbacher technology, signals an intent to move beyond conventional OSB into higher-value surface panels. The timeline for commissioning of the finishing line, followed by initial board production activity in 2026, indicates a deliberate ramp-up rather than an immediate volume play, consistent with a strategy centered on qualification, application development, and downstream acceptance.
In China, Luli Group represents a scale-oriented approach, with multiple fine OSB lines operational and expanded FOSB capacity coming online through additional fine-OSB lines. The company's emphasis on low-formaldehyde formulations and advanced continuous press technology reflects an alignment with furniture and construction requirements in domestic and export markets. This positions Luli as a player that can address volume demand while maintaining attention to surface and emission specifications.
GuangXi Dekek Group adopts a more specialized premium positioning. Its use of Dieffenbacher equipment, MDI adhesive options, and eucalyptus feedstock points to a product focus on fine surface panels for furniture and decorative uses. By concentrating on premium fine surface panels, Dekek illustrates how feedstock and adhesive choices can be combined with process technology to serve higher-specification end segments rather than competing primarily on commodity board characteristics.
West Fraser and Louisiana-Pacific contribute a different competitive logic. As large North American OSB manufacturers with broad structural and specialty panel portfolios, they bring extensive capacity, supply chain scale, and market access. Their relevance to FOSB lies partly in the structural OSB base that can support fine surface applications and engineered wood product development, offering the potential to leverage existing operational strengths while expanding into higher-value panel grades where requirements permit.
In Europe, Kronospan and Egger bring established wood-based panel expertise and broad construction and furniture market reach. Kronospan's capabilities in OSB with fine surface variants and Egger's wood-based material portfolio indicate that European producers are not merely following North American or Asian FOSB developments but are shaping their own product strategies around regional application needs, emission expectations, and finish requirements.
Market Evolution and Competitive Dynamics
The overall market structure suggests a landscape in transition. With the top five firms accounting for under 40 percent of revenue, there is room for both consolidation and specialist differentiation. New capacity additions in key producing regions indicate that growth is being pursued not only by incumbents expanding within existing footprints but also by producers building dedicated fine surface lines to capture specific application demand. This points toward a market that is likely to remain somewhat fragmented at the global level while becoming more concentrated within premium FOSB niches where technology, feedstock, and qualification matter most.
Competitive advantage is increasingly likely to come from three intertwined elements: the ability to deliver consistent fine surface quality at scale, the capacity to meet low-emission expectations without compromising cost, and the strength of application-specific relationships with furniture manufacturers, construction specifiers, and industrial buyers. Firms that treat FOSB as a distinct product category with its own technical and commercial requirements are better positioned than those that view it simply as a subset of general OSB production.
OSB Sheathing Market
Future Outlook: Trends and Opportunities
Looking ahead to the 2026-2032 period, several interconnected trends are likely to shape the FOSB market and define where commercial value accrues.
The first trend is the gradual narrowing of FOSB's application footprint around segments where its combination of surface quality and structural performance delivers a clear advantage. Rather than displacing all competing boards, FOSB is likely to gain traction in furniture parts, interior fit-out components, and certain construction applications where surface finish, stability, and machining behavior are critical. This selective adoption will reward producers that invest in application development and specifiers' education rather than relying solely on board-level marketing.
The second trend is the growing importance of adhesive technology and emission performance as baseline expectations. As low-formaldehyde and formaldehyde-free options become more common in premium FOSB lines, producers that can control resin usage, achieve consistent bonding, and document emission performance will be better equipped to serve regulated interior markets. This trend also creates opportunities for differentiation through product documentation, testing, and specification support, especially in markets where compliance is expected but implementation quality varies.
Oriented Strand Board (OSB) Market
The third trend concerns supply chain and cost management. With wood and adhesive inputs remaining sensitive to broader commodity dynamics, producers that optimize feedstock mix, press efficiency, and surface layer application are likely to manage margins more effectively. In parallel, regional pricing conditions will continue to influence competitive attractiveness across geographies, meaning that market entry and expansion decisions will need to account for local feedstock availability, logistics, and downstream pricing power.
These trends translate into tangible commercial opportunities. For producers, the opportunity lies in converting technological capability into recognized application fit, particularly in furniture and interior construction, where surface and emission attributes can support value-based positioning. For investors, the opportunity is to distinguish between capacity that is aimed at commodity substitution and capacity that is designed to serve premium fine surface demand with defensible technical and supply chain advantages. For procurement and specification teams, the opportunity is to use FOSB selectively where it reduces downstream processing cost, improves finished-product quality, or enables design choices that are harder to achieve with traditional boards.
Potential risks and uncertainties should not be overlooked. Substitution pressure from MDF, particleboard, and improved OSB grades remains real, particularly where FOSB does not offer a sufficiently compelling cost or performance advantage. Feedstock and adhesive cost volatility can compress margins if not managed proactively. In addition, regulatory expectations may continue to rise, shifting the baseline for what qualifies as acceptable performance and increasing the cost of non-compliance. These factors suggest that confidence in long-term FOSB growth should be paired with disciplined application targeting and cost control.
Strategic Recommendations for Decision-Makers
For manufacturers, the priority is to define FOSB as a distinct product platform rather than a generic panel. This means aligning technology investment, feedstock strategy, and adhesive selection with specific end-use requirements, and building qualification and specification support that helps buyers understand where FOSB adds value. Producers that can demonstrate consistent surface quality, predictable emission performance, and reliable supply are better positioned to secure long-term relationships in furniture and interior construction segments.
For investors, due diligence should focus on the fit between capacity strategy and application reality. The most attractive opportunities are likely to be found where new lines are tied to clear downstream demand, supported by appropriate press and surface technology, and managed with cost structures that can withstand input volatility. Broader OSB capacity expansions should be evaluated separately from dedicated FOSB projects, since the commercial logic and risk profile differ meaningfully.
For procurement and specification teams, the practical path is to evaluate FOSB on a segment-by-segment basis, comparing total installed cost, finish compatibility, machining behavior, and compliance attributes against entrenched alternatives. Where FOSB offers a genuine combination of surface quality, structural performance, and supply reliability, it can be a constructive option; where it does not, traditional boards may remain the better choice.
For stakeholders seeking a deeper, segment-level view of market size, regional dynamics, and company-level positioning, the full PW Consulting report provides structured detail and customized interpretation to support internal planning and investment decisions.
For detailed analysis of this topic, please visit the official page: Fine Surface Oriented Strand Board (FOSB) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Nb Alloys Market: Why 7.03% CAGR and Asia Pacific's Rise Redefine Growth
By PW Consulting, 2026-09-18
Strategic Trends and Commercial Opportunities in the Worldwide Nb Alloys Market
The global niobium alloys market has demonstrated robust expansion over the past five years, driven by sustained demand from high-performance industrial sectors and critical infrastructure applications. Valued at approximately $530 million in 2020, the market reached $740 million by 2025, reflecting a compound annual growth rate that positions the sector for continued momentum through the end of the decade. Projections indicate that revenue will surpass $1.19 billion by 2032, underpinned by a steady growth trajectory of 7.03 percent annually. This expansion is not merely a function of macroeconomic recovery but stems from structural shifts in how advanced materials are specified, sourced, and integrated into next-generation engineering solutions.
At the heart of this growth lies a concentration dynamic that shapes both opportunity and vulnerability. The top three players control roughly 78.5 percent of market revenue, while the top five entities account for 86.2 percent, indicating a highly consolidated landscape where strategic positioning carries disproportionate weight. Such concentration reflects the capital-intensive nature of niobium extraction, refining, and alloy production, as well as the specialized technical expertise required to meet demanding application standards. For decision-makers, this means that supply security, qualification pathways, and long-term supplier relationships are not operational details but strategic imperatives.
Despite the favorable growth outlook, the industry stands at a critical juncture shaped by three interconnected challenges. First, raw material cost volatility has introduced margin pressure across the value chain. Ferroniobium pricing hovered around $42,500 per metric ton in 2023, driven largely by concurrent steel alloy demand, creating upstream cost fluctuations that cascade into downstream alloy formulations. Second, regulatory and compliance frameworks are tightening at a pace that requires proactive adaptation. Environmental and safety standards, particularly around mining operations and material purity thresholds, are reshaping permissible supply routes and adding complexity to qualification processes. Third, logistics disruptions have exposed fragility in export corridors. Port surcharges and routing inefficiencies have added 5-7 percent to export costs in certain periods, directly impacting landed costs for internationally sourced alloy feedstocks. Together, these forces demand that market participants move beyond passive procurement models toward more resilient, transparent, and strategically aligned sourcing architectures.
Key Drivers Shaping Market Trajectory
Technical Innovation and Material Performance Breakthroughs
The most compelling growth catalyst in the niobium alloys sector stems from continuous material science advancement. Niobium-titanium and niobium-zirconium systems remain foundational for superconducting applications, but recent engineering iterations have expanded their operational envelopes. The introduction of certified alloy variants tailored for high-field magnetic resonance imaging magnets exemplifies how incremental compositional optimization can unlock immediate commercial demand. When a supplier launches a formulation that meets stringent superconducting performance criteria while maintaining manufacturability, it does not merely add a product line; it opens a new procurement pathway for medical equipment manufacturers who require predictable electromagnetic properties at scale.
Beyond superconductivity, high-temperature stability and corrosion resistance continue to drive alloy development for extreme-environment applications. Sintered niobium composites and vacuum-remelted microstructures are increasingly specified for furnace components, sputtering targets, and chemical processing equipment where failure tolerance is non-negotiable. These technical improvements translate directly into longer service life, reduced maintenance cycles, and lower total cost of ownership for end users, which in turn reinforces repeat procurement and specification lock-in. The implication for commercial strategy is clear: differentiation is increasingly tied to validated performance data, certification readiness, and the ability to support engineering teams during material selection phases.
Policy and Regulatory Evolution
Regulatory dynamics are no longer peripheral considerations; they actively shape sourcing feasibility and market access. Environmental oversight of mining operations has intensified, with regulatory bodies mandating stricter tailings dam safety protocols following post-2022 audit cycles. While these measures improve long-term operational sustainability, they also compress short-term supply flexibility and elevate compliance costs for producers operating in affected jurisdictions. Simultaneously, chemical regulatory frameworks such as EU REACH impose material purity thresholds that restrict the use of niobium alloys containing certain impurity levels in consumer-facing applications. Such mandates do not shrink the market; rather, they redirect it toward certified, traceable, and technically compliant supply streams.
This regulatory tightening creates a bifurcation effect. Suppliers that invest early in documentation, purity control, and certification infrastructure gain preferential access to regulated markets, while those relying on ad hoc compliance face increasing friction. For procurement leaders, this means that supplier qualification cannot be reduced to price and lead time alone. Material traceability, regulatory alignment, and the ability to provide evidence of compliance are becoming table stakes in competitive bidding environments, particularly for medical, nuclear, and aerospace-grade applications.
Demand-Side Shifts in Critical Sectors
Demand growth is being shaped less by broad-based industrial expansion and more by concentrated, high-value application clusters. Aerospace and defense continue to represent the largest application share, reflecting the material's role in structural and propulsion components where weight-to-strength ratios and thermal performance are decisive. However, equally significant is the rising specification of niobium alloys in medical devices and superconductivity infrastructure, where precision, biocompatibility, and magnetic performance drive procurement decisions. Chemical processing and nuclear energy applications further contribute to demand stability, albeit at more niche volumes, by requiring alloys that withstand corrosive environments and radiation exposure without degradation.
What distinguishes the current demand cycle is the shift toward qualification-driven procurement. Engineering teams are increasingly reluctant to qualify new materials unless the supplier can demonstrate consistent microstructure control, reproducible mechanical properties, and robust quality management systems. This behavior does not slow demand; it concentrates it among suppliers that can offer verifiable technical endorsements. The commercial consequence is that market share expansion is becoming less about volume pricing and more about engineering trust, repeat qualification, and strategic co-development relationships.
Supply Chain and Cost Structure Dynamics
The niobium supply chain remains geographically concentrated, with Brazil accounting for the overwhelming majority of global mine production. This geographic concentration provides scale advantages but also introduces structural dependency on a limited set of mining and processing hubs. When coupled with export logistics friction, such as port surcharges and route disruptions, the result is a supply environment where cost predictability requires active risk management rather than passive contracting. Logistics exposure is not merely a transportation issue; it influences inventory strategy, regional buffer stocking, and the economics of local versus imported alloy forms.
Cost structures are also being reshaped by the interplay between ferroniobium feedstock pricing and downstream alloy conversion. Because a significant share of mined niobium flows into steel alloy applications, primary material pricing often reflects broader metallurgy demand rather than specialty alloy requirements alone. This dynamic means that specialty alloy producers must navigate upstream cost signals that are partially decoupled from their own demand cycles. Companies that secure long-term feedstock arrangements, optimize conversion yields, or integrate vertically where feasible are better positioned to maintain margin stability through price cycles.
Competitive Landscape and Leading Strategies
Incumbent Positioning and Differentiation Pillars
The market's concentrated structure has produced a set of incumbents whose strategies reflect distinct differentiation paths. The largest producer operates from a scale and feedstock dominance perspective, maintaining a near-ubiquitous position in ferroniobium supply for steel and superalloy applications. This positioning is reinforced by recent capacity expansions that increase oxide production volumes, ensuring feedstock availability for downstream alloy manufacturers. Scale leadership here is not just about tonnage; it is about supply reliability, pricing influence, and the ability to absorb demand fluctuations without disrupting customer schedules.
In contrast, specialized metallurgical groups differentiate through application-grade alloy expertise. Their vacuum arc remelting capabilities and targeted product launches for superconducting and aerospace use cases illustrate a strategy centered on technical precision rather than volume dominance. By introducing certified variants that meet specific magnet and structural requirements, these players convert technical capability into procurement preference. Their growth narrative is built on reproducibility, certification readiness, and the ability to serve demanding engineering specifications that generic feedstock suppliers cannot easily replicate.
Other significant players pursue diversification within the niobium value chain. Some focus on sintered alloys and sputtering targets for high-temperature industrial use, while others emphasize ingot, powder, and implant-grade supply chains for electronics and medical applications. A further cluster of producers ties expansion to mining-linked feedstock integration, leveraging resource access to stabilize input costs and support alloy output. Meanwhile, niche suppliers specializing in vacuum-melted alloys for nuclear and chemical processing equipment differentiate through application-specific material grades and long-standing qualification relationships. Each strategy is viable, but durability depends on execution consistency and the ability to align product development with procurement cycles in target end markets.
PW Consulting
Strategic Evolution of the Landscape
The competitive environment is evolving along three observable trajectories. First, capacity and capability expansion among incumbents signals a push to protect feedstock positioning and capture incremental demand without ceding technical differentiation to smaller rivals. Second, product-level innovation continues to fragment the market at the application layer, with certified medical-grade alloys and specialized superconducting variants creating sub-markets where qualification leadership translates into pricing power and stickier customer relationships. Third, regulatory and logistics pressures are encouraging more deliberate supplier selection, which benefits established players with documented compliance records and penalizes those lacking traceability or certification depth.
Integration and partnership dynamics are also gaining prominence. Where vertical integration is feasible, it provides cost and supply certainty; where it is not, long-term offtake agreements and technical co-development arrangements serve as alternatives to secure feedstock and align product roadmaps with downstream requirements. For new entrants, the barrier is less about conceptual feasibility than about qualification time, certification burden, and the trust required to displace incumbents in engineered applications. As a result, market evolution is likely to remain consolidation-heavy at the top while allowing targeted differentiation at the application and grade level.
Forward Outlook: Trends and Commercial Implications
Trend One: Qualification-Led Demand Concentration
Over the next three to five years, procurement behavior in high-value applications will continue to reward suppliers with established qualification footprints. As engineering teams face tighter project timelines and higher performance expectations, the cost of material re-qualification becomes a deterrent to supplier switching. This will reinforce demand concentration among incumbents and well-documented specialists, while creating entry opportunities only where new materials solve demonstrable performance gaps or cost-performance tradeoffs. The commercial opportunity lies in positioning product development around validated performance claims, certification readiness, and engineering support services that accelerate customer adoption.
Trend Two: Compliance as a Competitive Filter
Regulatory and purity requirements will increasingly function as competitive filters rather than mere compliance exercises. Suppliers that proactively align with tailings safety expectations, export compliance, and impurity thresholds will secure preferential access to regulated regions and applications. Conversely, those treating compliance as retrospective will face longer qualification cycles and growing procurement friction. Businesses that invest in traceable supply chains, documented purity control, and forward-looking regulatory monitoring will be better positioned to win tenders in medical, nuclear, and consumer-adjacent markets where material specifications are becoming more stringent.
High Performance Alloys Market
Trend Three: Feedstock Security and Margin Resilience
Cost and supply resilience will remain central to profitability, particularly as ferroniobium feedstock pricing continues to reflect broad metallurgy demand cycles. Organizations that secure stable feedstock access, optimize conversion efficiency, or align procurement geography with logistics realities will be better equipped to protect margins through volatility. At the same time, regional sourcing diversification and inventory buffering strategies will gain importance as export cost variability persists. The strategic implication is that resilience is not a back-office function but a competitive differentiator that influences pricing confidence, delivery reliability, and customer retention.
These trends carry inherent uncertainty. Geopolitical logistics disruptions, regulatory shifts, and raw material price swings can alter cost structures and demand timing unexpectedly. Market participants should therefore treat forecasts as directional guides rather than fixed trajectories, and build flexibility into sourcing, inventory, and product roadmaps accordingly.
Strategic Recommendations for Decision-Makers
For Manufacturers and Alloy Producers
Prioritize qualification depth and technical documentation as commercial assets. Invest in reproducibility, certification readiness, and engineering support that reduces adoption friction for demanding applications. Where feasible, secure feedstock arrangements or conversion optimizations that insulate margins from upstream pricing volatility, and align product development with the performance priorities of aerospace, medical, superconducting, and nuclear end users rather than competing solely on volume pricing.
For Investors and Capital Allocators
Evaluate opportunities through the lens of supply resilience, regulatory alignment, and application-specific differentiation rather than broad market growth narratives alone. Companies with credible compliance records, traceable supply chains, and targeted product certifications are better positioned to capture premium demand and sustain margins. Monitor capacity expansion signals, feedstock access strategies, and logistics exposure, as these factors will increasingly determine which players can convert market growth into durable profitability.
For Procurement and Supply Chain Leaders
Treat supplier selection as a multidimensional risk and performance decision. Price and lead time remain important, but traceability, certification status, purity control, and logistics resilience are increasingly decisive in strategic sourcing. Diversify supply geography where practical, maintain buffer strategies for critical alloy grades, and require evidence of compliance readiness from suppliers serving regulated applications. Proactive supplier qualification now reduces disruption and cost volatility later.
Superalloy Market
For organizations seeking deeper segmentation, regional supply dynamics, and tailored strategic scenarios, a full market research report provides the granular data and structured analysis needed to translate these trends into actionable plans.
For detailed analysis of this topic, please visit the official page: Worldwide Nb Alloys Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Global E-Government Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview and Core Challenges
The worldwide e-government market has entered a phase of accelerated transformation, driven by sustained public sector investment in digital infrastructure and shifting citizen expectations. Between 2020 and 2025, the market expanded from approximately $15.2 billion to $26.5 billion, reflecting a compound annual growth rate of 11.5 percent. Projections indicate this momentum will continue through 2032, with revenues climbing toward $56.8 billion by the end of the forecast period. This trajectory underscores a structural shift in how governments procure, deploy, and manage digital services, moving beyond isolated IT modernization projects toward integrated ecosystems that span identity management, service delivery, and data governance.
eDiscovery Market
Regional dynamics reveal a market that is both broad and uneven. North America maintains a leading position, supported by mature digital procurement frameworks and high public sector IT budgets. Europe follows closely, shaped by cross-border interoperability mandates and strong regulatory alignment. Asia Pacific represents a rapidly scaling region, where population size, urban digitization, and varying stages of administrative modernization create diverse demand patterns. Latin America and the Middle East and Africa, while smaller in absolute terms, are experiencing incremental adoption driven by targeted modernization initiatives and international development partnerships.
Despite this growth trajectory, the sector faces several structural challenges that determine which initiatives scale and which stall. First, legacy system integration remains a persistent barrier. Many agencies operate decades-old platforms that were never designed for cloud interoperability, API-based service chaining, or real-time data exchange. Upgrading these environments requires not only technology replacement but also process redesign, workforce reskilling, and careful data migration strategies. Second, cybersecurity and data sovereignty requirements are intensifying. Governments increasingly treat citizen data as a protected national asset, which means vendors must demonstrate robust encryption, identity verification, and compliance with local data residency rules. Third, digital inclusion and service accessibility remain uneven. High online service adoption in advanced economies contrasts with regions where connectivity gaps, language diversity, and varying digital literacy levels limit effective service reach. These challenges are not merely operational; they shape procurement decisions, vendor selection criteria, and the pace at which new platforms can be deployed at scale.
Key Drivers Shaping Market Evolution
Technology innovation continues to be the most visible catalyst for change. Cloud adoption has shifted from a cost optimization discussion to a foundational architecture choice for public sector digital services. In manyOECD countries, cloud infrastructure now represents a substantial share of e-government ICT budgets, reflecting the need for elastic compute, centralized data management, and faster service deployment. Alongside this shift, artificial intelligence and automation are being embedded into citizen-facing workflows. Predictive analytics are improving case routing and service personalization, while generative tools are being tested for document drafting, policy summarization, and internal productivity. However, the real differentiator is not the presence of AI alone but the ability to govern it responsibly. Public sector buyers are prioritizing platforms that offer transparency, auditability, and compliance controls, which is why governance-oriented AI tooling has gained attention among agencies seeking to balance innovation with accountability.
Policy and regulatory environments are equally influential. Governments are no longer treating digital transformation as a discretionary modernization effort; it is increasingly tied to national competitiveness, service resilience, and citizen trust. Regulatory frameworks are pushing vendors and agencies toward stricter security postures. For example, the US federal zero-trust strategy sets a clear direction for cybersecurity architecture, requiring agencies to adopt identity-centric access controls and continuous verification across e-government systems. In Europe, the Digital Services Act has introduced broader transparency and risk management expectations that affect online intermediaries and platforms supporting public service delivery. Meanwhile, data localization requirements in certain markets add complexity for multinational providers, forcing them to adapt deployment models, data storage arrangements, and compliance documentation to meet jurisdiction-specific rules. These policy shifts raise the bar for entry, but they also reward vendors that can demonstrate verifiable compliance and secure architecture at scale.
Demand-side behavior is changing as well. Citizens and businesses increasingly expect government services to match the responsiveness and usability of private-sector digital experiences. Mobile-first portals, self-service transaction flows, and personalized service journeys are becoming baseline expectations rather than differentiators. At the same time, workforce expectations inside government are evolving. Public sector teams want tools that reduce manual processing, improve inter-agency coordination, and provide clearer visibility into service performance. This demand pressure is encouraging agencies to move away from fragmented point solutions toward platforms that connect identity, case management, payments, and engagement tools in a more unified way.
Cost structures and procurement models are also being reshaped by the shift toward cloud and subscription-based delivery. Traditional on-premises deployments still play a role, particularly in contexts with strict data control requirements or existing infrastructure commitments, but cloud-based models are gaining share because they reduce upfront capital burden and allow agencies to scale services as demand fluctuates. This transition changes how vendors compete. Instead of winning large one-time license deals, providers are increasingly evaluated on long-term operational value, integration capability, security assurance, and total cost of ownership across the service lifecycle. The result is a market where differentiation comes less from feature count and more from reliability, compliance readiness, and the ability to support sustained digital service delivery.
Competitive Landscape and Leading Strategies
The competitive field is dominated by providers with strong public sector credentials, cloud infrastructure advantage, and the ability to connect digital services to broader transformation programs. Large platform companies have focused on offering secure government cloud environments, identity and data management tools, and application layers that support citizen portals and administrative workflows. Their strategic advantage lies in scale, global delivery capacity, and the ability to embed security, compliance, and analytics into a common architecture. This makes them particularly relevant for agencies seeking to modernize broad portfolios of services rather than isolated functions.
PW Consulting
Differentiation among leading players increasingly centers on how well they address government-specific requirements. Some vendors emphasize sovereign or government-dedicated cloud regions that support data residency and compliance obligations. Others focus on analytics and AI-enabled decision support, targeting the operational needs of agencies that want better insight into service demand, case handling, and citizen engagement. Specialist providers occupy an important position as well, particularly where deep domain expertise in permitting, licensing, payments, or civic engagement creates a stronger fit for specific agencies and local government contexts. These players often compete by offering purpose-built workflows, rapid deployment models, and long-standing relationships with public sector customers.
Recent market activity reflects a landscape that is both consolidating around platform plays and fragmenting through specialized solutions. Product and platform updates have focused on strengthening secure data processing, improving predictive capabilities for citizen services, and expanding governance tooling for public sector AI use. At the same time, contract awards and implementation wins show that demand is shifting toward cloud-based permitting, licensing, and service delivery platforms that can be scaled across multiple jurisdictions. International benchmarks also matter. High-performing e-government ecosystems tend to combine strong online service delivery with reliable digital identity and infrastructure, which reinforces the competitive importance of integrated offerings rather than standalone tools.
Looking ahead, the competitive environment will likely continue to evolve along three lines. First, larger platform providers will push further into verticalized government solutions, using their cloud and data foundations to deliver end-to-end service experiences. Second, specialized vendors will seek to defend their position by deepening domain depth, improving interoperability with larger platforms, and building implementation credibility across repeated public sector deployments. Third, services-led integrators will remain critical because many e-government programs depend on process redesign, change management, data migration, and cross-agency coordination, not just software installation. In this environment, the most successful players will be those that can combine technology with public-sector delivery discipline, compliance assurance, and measurable service outcomes.
Future Trends and Commercial Opportunities
Over the next three to five years, one of the most consequential trends will be the maturation of digital identity as a core component of e-government architecture. As online services expand, secure and convenient identity verification will become the gateway to citizen access, benefit distribution, tax processing, and regulatory engagement. This creates opportunities for providers that can offer strong authentication, privacy-conscious design, and interoperability across agencies and, in some cases, across borders. Identity is not just a security function; it is an enabler of service efficiency and trust.
A second trend is the growing emphasis on AI-enabled service operations with explicit governance controls. Governments are likely to adopt AI in targeted areas first, such as case triage, document handling, internal knowledge retrieval, and service demand forecasting. The commercial opportunity lies in solutions that integrate AI into existing public sector workflows while offering audit trails, policy controls, and human-in-the-loop oversight. Providers that can demonstrate responsible use, compliance readiness, and operational reliability will be better positioned than those competing primarily on novelty.
A third trend is the continued shift toward integrated citizen engagement and service delivery platforms. Agencies are under pressure to reduce friction across channels, improve transparency, and make services more accessible. This favors platforms that connect identity, case management, communications, payments, and performance analytics in a cohesive manner. Commercial value will accrue to vendors that can help agencies move from siloed digital tools to service journeys that are easier for citizens to navigate and easier for governments to manage.
These trends carry risks. Implementation complexity can delay value realization, especially when programs require legacy modernization and cross-agency coordination. Regulatory change may alter data handling requirements or security expectations faster than procurement cycles can adapt. Cybersecurity threats remain persistent, and any high-profile failure in public service reliability can undermine confidence in digital transformation efforts. In addition, uneven digital access can create adoption gaps that limit the impact of otherwise well-designed platforms. Companies entering or expanding in this market should plan for long sales cycles, multi-stakeholder evaluation processes, and the need to prove outcomes beyond technical capability.
Worldwide Information Technology Market
Strategic Implications for Decision-Makers
For technology and solution providers, the priority is to align offerings with government procurement realities and compliance expectations. Products that combine secure cloud deployment, identity and access capabilities, and clear governance features will have an advantage in markets where agencies are balancing innovation with risk management. Equally important is delivery capability: public sector buyers continue to value proven implementation approaches, interoperability with existing systems, and support for workforce transition. Companies that can articulate measurable service improvements, not just technical specifications, will differentiate more effectively.
For investors, the market signals a preference for businesses with defensible public sector relationships, recurring revenue models, and the ability to operate across complex regulatory environments. Interest is likely to concentrate on platforms and integrators that can sustain long-term engagements through cloud migration, digital identity, service modernization, and AI-enabled operations. Due diligence should pay close attention to compliance readiness, data handling practices, and the quality of government clientele, since these factors often determine whether a provider can scale beyond initial pilot deployments.
For government agencies and public sector buyers, the most effective path is to prioritize architectural coherence over fragmented tool accumulation. Investments that strengthen identity, security, data interoperability, and citizen engagement foundations tend to create more durable value than isolated feature upgrades. Procurement teams should evaluate vendors on total lifecycle cost, integration capacity, security posture, and the ability to support inclusive service delivery. In fast-moving areas such as AI and cloud transformation, starting with well-scoped use cases and clear governance rules can reduce risk while building organizational capability for broader rollout.
Given the speed of policy change, regulatory divergence, and platform evolution, decision-makers benefit from continuous market intelligence that tracks vendor moves, compliance shifts, and regional adoption patterns in detail. A broader research view can help organizations validate assumptions, compare subsegments, and refine entry or investment strategies with greater precision.
For detailed analysis of this topic, please visit the official page: Worldwide E-Government Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The Real Drivers Behind Bismuth Ingot Market's 5.45% CAGR Trajectory to 2032
By PW Consulting, 2026-09-18
Strategic Trends & Commercial Opportunities in the Worldwide Bismuth Ingot Market
Market Snapshot: Growth Dynamics and Structural Constraints
The global bismuth ingot market has entered a phase of sustained expansion, driven by resilient demand across specialty alloys, pharmaceuticals, and high-purity industrial applications. With a compound annual growth rate of 5.45% projected through 2032, the sector is transitioning from a niche minor-metal segment to a strategically significant component of advanced manufacturing supply chains. This trajectory reflects not only incremental volume growth but also an upward recalibration of value, as producers capture premiums for higher purity grades and more consistent metal specification.
Despite the optimistic forward curve, the industry operates under structural constraints that define both its near-term volatility and its long-term evolution. One of the most defining characteristics of the market is its byproduct dependency. Bismuth is overwhelmingly recovered from lead, copper, tungsten, or zinc processing streams rather than from primary extraction dedicated solely to bismuth. This means supply responsiveness is inherently lagged and partially decoupled from downstream demand signals. Producers cannot simply commission new capacity to chase price rallies; additional volumes must align with broader smelting economics and base-metal market conditions.
A second structural challenge lies in geographic concentration and regulatory friction. Production is heavily clustered in regions where lead and nonferrous smelting infrastructure is mature, and where the mineral endowment supports integrated metal recovery. Recent policy actions in key producing jurisdictions have added a new layer of complexity. Export controls and licensing requirements on bismuth metal and related products have tightened global availability, contributed to price volatility, and forced downstream buyers to rethink procurement logic. The combination of concentrated supply, policy-driven disruption, and byproduct-linked production creates an environment where inventory management, qualification cycles, and substitution readiness become critical operational disciplines.
A third challenge is the widening gap between standard and high-purity supply. Demand for controlled-purity bismuth ingots is accelerating in electronics, semiconductor-adjacent processes, and specialty catalysts, yet the metallurgy to reach and validate elevated purity grades is not uniformly available across smelters and refiners. This creates a bifurcated market. Lower-specification ingots may move through commodity-oriented channels, while high-purity material often requires traceability, process validation, and long-term offtake alignment. The result is a market where commercial success is increasingly tied to technical capability and qualification infrastructure rather than volume alone.
Key Drivers Reshaping the Bismuth Ingot Landscape
Technological Innovation in Refining and Purity Control
Metallurgical progress is one of the clearest value-creation vectors in the bismuth ingot market. Test work and process optimization efforts have demonstrated that concentrated leachates can be transformed into high-purity ingots through integrated leaching, cementation, and pyrometallurgical refining pathways such as liquation, sulphuration, and chlorination. These process refinements matter commercially because they can improve yield consistency, reduce equipment footprint, and lower the unit cost of reaching target purity.
For downstream users, this translates into a more reliable pathway to 4N-grade and above material without relying solely on legacy refining operations that were designed around older product specifications. In high-value applications, small improvements in purity control can be the difference between qualification approval and procurement rejection. The broader implication is that refining competence is becoming a strategic asset. Producers that can demonstrate repeatable purity outcomes, supported by metallurgical validation and controlled process parameters, are better positioned to serve electronics, pharmaceutical-adjacent users, and specialty alloy makers that require specification integrity rather than occasional bulk availability.
Policy, Trade Controls, and the Reorientation of Procurement
Regulatory developments have shifted bismuth from a relatively stable minor metal into a material with explicit strategic trade sensitivity. Export controls on bismuth metal and products, introduced in response to broader tariff dynamics, have influenced global supply tightness and price behavior. In parallel, defense-related procurement activity has surfaced as a notable demand signal, with government agencies issuing tenders for high-purity bismuth in slab or ingot form for stockpile purposes.
These developments do more than move prices. They change the incentives for supply chain design. Buyers that previously treated bismuth as a readily available minor commodity are now factoring in geographic diversification, supplier qualification, and contractual flexibility. At the same time, the concentration of refinery production in one dominant producing region amplifies the effects of policy shifts. When a major share of global refined material flows from a limited set of countries, trade frictions can quickly propagate into lead times, price discovery, and inventory strategy.
For executives, the strategic takeaway is that regulatory risk has become a procurement variable, not just a compliance concern. Flexible sourcing, dual-supplier strategies, and reserves planning are increasingly relevant, especially for applications where substitution is technically constrained or where qualification cycles are long.
Demand-Side Shifts in Specialty Alloys, Pharmaceuticals, and Electronics
Demand growth is being pushed by a cluster of application trends rather than a single volume driver. In fusible alloys and solders, bismuth continues to serve as a functional substitute in formulations where lower melting points, density characteristics, or environmental constraints matter. In pharmaceuticals and related chemical applications, bismuth-based compounds and metal inputs remain embedded in product lines that depend on controlled specifications and consistent supply. In pigments, electronics, and specialty metallurgical uses, the need for purity assurance is intensifying as downstream processes become more sensitive to impurity profiles.
What makes this demand environment distinctive is that it rewards reliability and specification control more than it rewards cheap availability. A pharmaceutical or high-purity electronics supply chain does not respond in the same way as a generic alloy market. Qualification lead times, documentation, lot consistency, and technical support all influence purchasing decisions. As a result, application growth in higher-value segments is strengthening the commercial logic of dedicated high-purity production and long-term customer relationships, even when total tonnage remains comparatively modest relative to base metals.
Supply Chain Structure and Cost Dynamics
Cost and availability in the bismuth ingot market are shaped less by standalone mining economics than by the health and configuration of base-metal smelting. Because bismuth is primarily a byproduct, its supply is tied to the operational intensity of lead, copper, tungsten, and zinc circuits. This has two practical effects. First, bismuth availability can expand or contract depending on smelting throughput and concentrate processing decisions that are made for reasons unrelated to bismuth alone. Second, cost structures are influenced by the complexity of separation and refining, especially when higher purity grades are required.
Price behavior has also reflected this structural reality. Recent annual price levels have reached historically elevated averages, and warehouse pricing in key hubs has shown sharp intermittent peaks. Such movements indicate that the market is not only reacting to demand but also absorbing the effects of supply concentration, policy disruption, and the premium attached to specification-sensitive material. For producers, this creates an opportunity to capture value through purity differentiation and service reliability. For buyers, it underscores the importance of visibility into refining capacity, inventory positions, and the metallurgical route used to produce the ingots they purchase.
Competitive Landscape and Leadership Strategies
The competitive field in the bismuth ingot market is defined by a mix of integrated smelters, specialty refiners, and distributors with strong technical and application orientation. Concentration is meaningful, with a relatively small group of players accounting for a substantial share of market activity. This structure favors companies that combine production competence with application knowledge, purity control, and the ability to serve complex procurement requirements.
A clear pattern in the landscape is the divergence between byproduct-oriented smelting operations and more specialized minor-metal producers. Companies that recover bismuth from lead smelting or from battery-related recycling streams can benefit from existing infrastructure and scale, particularly when bismuth is packaged for alloys, industrial uses, and pharmaceutical-adjacent applications. Their strategic advantage often lies in established processing routes and the ability to supply material that aligns with ingot form requirements at commercial scale.
At the same time, high-purity specialists are positioning around purity assurance, traceability, and application-specific service. These producers focus on controlled grade architecture, working with customers in electronics, thin-film deposition, specialty alloys, and catalytic applications where specification integrity is paramount. Their differentiation typically comes from process discipline, lot documentation, custom formulations, and the capacity to bridge laboratory demand with bulk supply.
Another important evolution is the emergence of project-stage producers aiming for vertically integrated operations. One notable direction is the development of projects intended to produce high-purity bismuth ingots alongside cobalt, gold, and copper-related outputs. Recent milestones in these initiatives have included metallurgical test work validating 4N bismuth ingot production and progress on site control for hydrometallurgical processing. If such projects advance through construction decisions, they could add supply diversification and reinforce the strategic relevance of non-China refining outside traditional byproduct channels. For the market overall, these developments matter because they could introduce new sourcing geographies, new purity pathways, and additional optionality for buyers seeking to reduce concentration risk.
The competitive trend to watch is therefore not simply consolidation, but functional specialization. Some players will continue to compete on volume and integrated smelting economics. Others will compete on purity, qualification support, and reliability for high-specification buyers. The most strategically resilient firms are likely to be those that can navigate both worlds: producing material at meaningful scale while maintaining the technical credibility to serve demanding end-use segments.
Indium Market
Forward Outlook: Three Trends Shaping the Next 3-5 Years
The first likely trend is widening premium differentiation by purity and application readiness. As more customers in electronics, pharmaceuticals, catalysts, and specialty materials require documented purity and lot consistency, the market will increasingly separate standard commercial ingots from validated high-purity supply. This creates commercial opportunities for producers that can formalize quality systems, support qualification processes, and maintain stable grade control. It also raises the cost of entry for new suppliers targeting higher-value segments, since metallurgical competence and customer validation will be decisive.
Solar Ingot Wafer Market
The second trend is continued supply-side reconfiguration driven by policy and byproduct economics. Because bismuth availability is linked both to smelting dynamics and to trade policy, buyers should expect periodic tightening and price volatility rather than smooth, linear supply growth. At the same time, interest in refining diversification and project-stage development may gradually broaden geographic supply. The commercial implication is that procurement strategies will need to incorporate redundancy, qualification lead times, and scenario planning for regulatory change, especially where bismuth has no easy substitute.
The third trend is the growing strategic relevance of bismuth in resilience-focused procurement. Strong price signals and stockpiling interest point to recognition of bismuth as a material with both industrial and strategic value. For commercial players, this can mean stronger negotiating leverage for qualified producers, but also higher inventory expectations from some buyers. The uncertainty lies in the pace and direction of policy evolution, the timing of new project capacity, and whether base-metal smelting conditions remain favorable for consistent byproduct recovery. These variables will shape whether the market remains tight and premium-driven or opens up as new supply matures.
PW Consulting
Actionable Recommendations for Decision-Makers
For manufacturers and application developers, the priority is to treat purity specification and supplier qualification as core business variables rather than administrative requirements. Where applications depend on tight impurity control, building longer qualification cycles into planning, requesting documented metallurgical routes, and securing multi-source options can reduce exposure to supply shock and quality variability. Aligning product design with available purity grades can also unlock more stable sourcing and reduce substitution friction.
For investors and corporate development teams, the strategic opportunity lies in identifying where value is being created along the bismuth value chain. Premium capture is increasingly tied to refining capability, purity assurance, and access to demand segments that tolerate less substitution. Projects and producers that can demonstrate validated high-purity output, diversified supply logic, or strong application-oriented service may offer more durable positioning than volume-only plays in a market shaped by byproduct constraints and trade sensitivity.
For procurement and supply chain leaders, the recommendation is to move from transactional buying to structured resilience planning. That means mapping exposure to concentrated supply, evaluating inventory and stockpiling options where substitution is limited, and negotiating contracts that account for purity variability and lead-time risk. In a market where prices can react sharply to policy shifts and refining constraints, visibility into the supply base becomes a competitive advantage in its own right.
Detailed segment-level sizing, purity-grade dynamics, regional exposure, and company-specific operating profiles can materially sharpen these decisions. For teams that need deeper granularity on demand composition, refining pathways, and competitive positioning, the full market research report provides the dissection required to translate these trends into company-specific action.
For detailed analysis of this topic, please visit the official page: Worldwide Bismuth Ingot Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com